Global energy markets closed the month of August 2026 under intense pressure as crude oil prices resumed an upward trajectory, driven by escalating geopolitical friction and persistent threats to international supply chains. For Indonesia, an emerging market economy navigating a delicate balance between fiscal consolidation and domestic price stability, these developments carry profound implications. The fluctuation of international crude benchmarks directly ripples through the nation’s macroeconomic framework, threatening to alter energy import costs, fuel domestic retail prices, stoke inflationary pressures, and strain the state budget.
As of Monday, August 31, 2026, Brent crude—the international benchmark for oil pricing—was hovering around $90.41 per barrel. This notable price elevation occurred against a backdrop of heightened market anxiety, with traders and analysts closely monitoring vulnerabilities in critical maritime trade corridors and regional conflicts that threaten to disrupt the unhindered flow of petroleum from major producing regions to global consumers.
Anatomy of a Price Surge: Geopolitics Versus Demand Realities
The primary catalyst behind the late-August price rally is the heightened risk premium embedded into the global petroleum market due to localized conflicts and strategic chokepoints. Persistent uncertainties across the Middle East, particularly involving the security of maritime traffic passing through the vital Strait of Hormuz, have forced market participants to reprice the probability of sudden, severe supply contractions. The Strait of Hormuz remains a critical artery for world energy transport, and any operational impediments in the corridor immediately translate into fears of restricted global crude availability.
Paradoxically, this supply-side bullishness persists even as broader demand fundamentals present a more subdued picture. According to reports from Reuters, global oil demand for the full year of 2026 is projected to contract by approximately 1 million to 1.6 million barrels per day. This softening in global consumption is largely attributed to decelerating import demand from China, the world’s second-largest economy and a primary engine of historical energy consumption growth. Nevertheless, the acute specter of supply disruptions has easily overshadowed demand-side lethargy, keeping upward pressure firmly entrenched on international crude prices.
The Mechanics of Domestic Fuel Pricing: Nonsubsidized Versus Subsidized Sectors
In Indonesia, the transmission mechanism from international crude benchmarks to retail fuel prices at local gas stations is neither uniform nor automatic. The domestic market operates under a dual-pricing structure that separates nonsubsidized commercial fuels from government-regulated subsidized products.
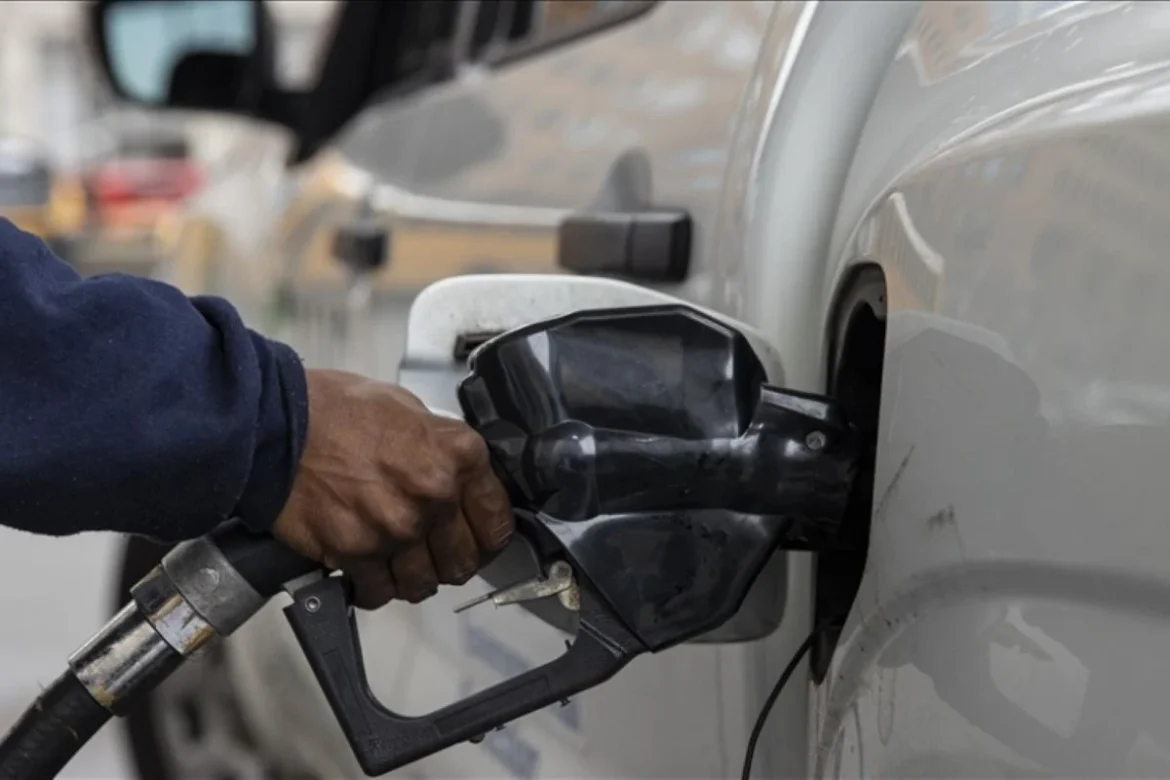
Nonsubsidized fuels, most notably Pertamax, are fundamentally tethered to international oil price movements and broader economic indicators. State-owned energy giant PT Pertamina (Persero) has consistently maintained that it actively monitors global crude trends as a foundational metric when determining retail adjustments for its commercial product lines. Concurrently, the Ministry of Energy and Mineral Resources (ESDM) calculates the economic pricing parameters for Pertamax by evaluating procurement costs, refining margins, logistics, and foreign exchange rates amidst ongoing global volatility. Consequently, while escalating global prices exert direct upward pressure on nonsubsidized offerings, actual price adjustments remain subject to a deliberative policy matrix involving both the government and corporate stakeholders.
In stark contrast, government-subsidized fuels such as Pertalite follow a completely insulated pricing architecture designed to protect the purchasing power of lower- and middle-income segments. Despite the climb in global prices toward the psychological $100-per-barrel threshold, executive leadership has maintained a resolute stance on shielding subsidized variants from external shocks. Minister of Finance Purbaya Yudhi Sadewa explicitly reaffirmed that the retail price of Pertalite will remain frozen, even if Brent crude reaches or exceeds $100 per barrel. This policy dichotomy ensures that while commercial consumers feel the pinch of global energy inflation almost immediately, the immediate fiscal buffer cushions the broader populace from severe inflationary spikes at the pump.
Macroeconomic Transmission: The Indonesian Crude Price and State Budgetary Pressures
The broader economic reverberations of fluctuating global oil markets in Indonesia are officially gauged through the Indonesian Crude Price (ICP), a monthly average benchmark calculated by the Ministry of ESDM based on a basket of actual Indonesian crude transactions. For July 2026, the ICP was officially recorded at $81.68 per barrel, registering a moderate decline from the $83.45 per barrel registered in June. However, with international markers climbing steeply toward the end of August, market watchers anticipate that subsequent ICP calculations will reflect these renewed global pressures.
The overarching concern for economic planners lies in the structural design of the State Budget (APBN). In the formulation of the 2026 APBN, the government established its baseline fiscal assumptions using an ICP target of $70 per barrel. When actual market realizations persistently outstrip this foundational baseline, the national treasury faces magnified fiscal vulnerabilities.
If global prices remain elevated over an extended horizon, the state faces a widening fiscal gap. This tension manifests primarily through ballooning energy subsidy and compensation expenditures, which the government must absorb to maintain fixed prices for Pertalite and subsidized liquefied petroleum gas (LPG). Beyond raw commodity costs, the ultimate health of the fiscal deficit is dictated by a complex matrix of variables, including the rupiah-to-dollar exchange rate, domestic fuel consumption volumes, non-tax state revenues (PNBP) from the upstream oil and gas sector, and dynamic fiscal intervention policies.
Inflationary Risks and Broader Industrial Implications
Beyond direct fiscal outlays, prolonged high energy costs carry significant secondary risks for domestic price stability. Energy is a foundational input for virtually every sector of the modern economy. When fuel and transportation costs escalate, logistics providers and industrial manufacturers face immediate margin compression.
The transmission of higher energy costs into the wider economy typically occurs via logistics and supply chain adjustments. Increased operational expenses for commercial trucking, maritime shipping, and urban transport fleets inevitably raise the cost of goods distribution. If businesses choose to pass these heightened overheads downstream to end-consumers, the result is a generalized rise in the cost of basic commodities, foodstuffs, and manufactured goods. This secondary inflation poses a direct threat to household purchasing power, particularly for vulnerable demographics whose discretionary spending is already limited.
For industrial enterprises, particularly those heavily reliant on heavy machinery, captive power generation, or fuel-intensive manufacturing processes, persistent high crude prices degrade profitability. Over the medium to long term, sustained energy shocks can compel industries to optimize operational efficiencies, delay capital expenditures, or recalibrate production targets to survive margin pressures.
Financial Markets and Investor Sentiment
The tremors of global energy volatility are similarly visible in Indonesia’s financial capital markets. Throughout late August 2026, domestic equity benchmarks, including the Jakarta Composite Index (IHSG), experienced bouts of downward pressure, tracking broader regional trends across Asia. Investor sentiment across emerging markets is frequently dampened by rising global energy prices, as foreign institutional investors weigh the adverse impacts of higher import bills and potential fiscal deterioration against corporate earnings growth. Analysts note that foreign capital outflows during periods of commodity turbulence often exacerbate local currency depreciation, creating a compounding cycle that further complicates the import economics of refined petroleum products.
Strategic Outlook: Navigating Uncertainty Through 2026
As international energy analysts, including those at Reuters, project that Brent crude could comfortably sustain levels above $80 per barrel throughout the remainder of 2026—provided geopolitical chokepoints remain contested—Indonesia faces a complex operational environment.
The current landscape underscores a fundamental economic reality: while global volatility does not automatically trigger a blanket increase in Indonesian fuel prices due to deliberate government shielding of subsidized goods, the broader macroeconomic ecosystem remains acutely sensitive to external shocks. Policymakers must continuously weigh the delicate trade-offs between maintaining consumer price stability, preserving the integrity of the state budget, and ensuring the long-term financial viability of state-owned energy enterprises. Ultimately, the ongoing energy market fluctuations serve as a stark reminder of the country’s structural exposure to geopolitical headwinds, requiring vigilant fiscal management and adaptive energy security strategies in the months ahead.