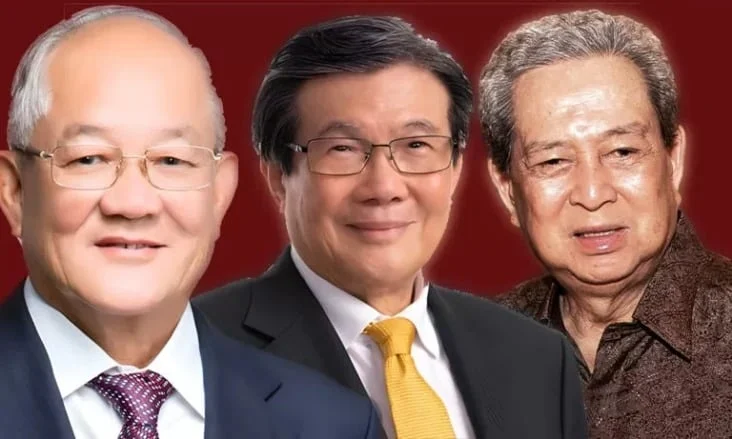
The collective wealth of Indonesia’s top five billionaires and their family members has evaporated by an astonishing USD 57 billion, equivalent to approximately IDR 1,033 trillion, following a severe and sustained downturn triggered by index provider MSCI Inc. The dramatic erosion of fortunes began when MSCI first issued a cautionary warning regarding a potential downgrade of Indonesia’s equity market status in January 2026. According to the Bloomberg Billionaires Index, the combined wealth of these prominent tycoons plummeted to USD 71.6 billion as of October 22, effectively wiping out every cent of wealth accumulation achieved over the preceding four years. This unprecedented financial contraction highlights the extreme volatility and vulnerability of emerging market valuations when subjected to systemic regulatory and index rebalancing pressures. Financial analysts and academic experts have noted that while the losses are staggering, a significant portion of this diminished wealth exists strictly on paper, tied inextricably to fluctuating equity valuations and highly concentrated corporate ownership structures.
Background Context: The MSCI Warning and Structural Vulnerabilities
The catalyst for this historic wealth destruction originated in early 2026, when MSCI Inc., a globally influential provider of equity indexes used by institutional investors worldwide, raised serious compliance and liquidity concerns regarding the Indonesian stock market. A potential downgrade by MSCI carries severe financial ramifications, as international funds tracking these indices are systematically mandated to rebalance their portfolios, which often leads to massive capital outflows from affected jurisdictions.
Layenda Kresna Bramanta, a finance lecturer at the Deakin-Lancaster Indonesia campus, elaborated on the mechanics of this decline in an interview with The Asia Business Daily. He emphasized that the severe valuation drops reflect the high sensitivity of controlling shareholdings in large Indonesian conglomerates to prevailing market sentiment. Furthermore, the Indonesian corporate landscape has historically been characterized by highly concentrated ownership, where founding families retain dominant stakes. While this structure fosters strong centralized leadership during bull markets, it exposes controlling shareholders to catastrophic downside risks when systemic shocks—such as a threatened MSCI downgrade—precipitate broad-based market sell-offs.
Chronology of Events: From Initial Warning to October 2026
The unfolding financial crisis can be mapped across a distinct timeline of escalating pressure on Indonesian equities:
- January 2026: MSCI Inc. issues its initial warning regarding the structural integrity, liquidity, and accessibility of the Indonesian equity market, sparking early apprehension among foreign institutional investors.
- Throughout Q1 and Q2 2026: Foreign capital begins steady outflows from the Jakarta Composite Index (IHSG), putting persistent downward pressure on blue-chip stocks and conglomerate valuations.
- Early October 2026: Key domestic tycoons execute emergency liquidity measures and block trades at steep discounts, signaling acute financial distress among ultra-high-net-worth individuals.
- October 22, 2026: Bloomberg Billionaires Index data reveals that the combined net worth of Indonesia’s top five billionaires has dropped to USD 71.6 billion, recording a cumulative loss of USD 57 billion since January.
- October 27, 2026: Financial experts and market analysts formally evaluate the broader economic implications of the paper wealth wipeout, noting that the IHSG has fallen 38% year-to-date.
Individual Impact: Heavy Losses Among Indonesia’s Elite Tycoons
The market correction has disproportionately impacted Indonesia’s most established billionaires, with each experiencing severe contractions in their respective corporate empires.
Prajogo Pangestu, the visionary founder of petrochemical and energy giant Barito Pacific, suffered the single largest monetary loss among his peers. Pangestu’s net worth has plummeted by more than 60% since January 27. Despite this staggering contraction, he manages to retain his position as the second-richest person in Indonesia, holding an estimated net worth of approximately USD 15 billion. His conglomerate, which saw meteoric rises in previous years driven by green energy transitions and petrochemical expansions, bore the brunt of aggressive institutional portfolio reallocations.
Meanwhile, Budi Hartono, the controlling shareholder of Djarum Group and a principal stakeholder in Bank Central Asia (BCA)—one of the nation’s most robust private lenders—saw his personal wealth diminish by over USD 5 billion, representing a 31% reduction from his peak holdings. Compounding the family’s financial contraction, other members of the Hartono family collectively shed an additional USD 5 billion in net worth over the same period, reflecting broad-based weakness across their banking, tobacco, and digital investment portfolios.
Coal tycoon Low Tuck Kwong experienced an equally dramatic reversal of fortune. His net worth plunged by 54%, leaving him with an estimated USD 10 billion. The sharp decline in Low’s wealth was accelerated by a high-profile transaction earlier in the month, when he and his daughter executed a large block sale, offloading approximately 30% of their equity stake in Bayan Resources. Crucially, the transaction was executed at a massive discount—more than 80% below the previous day’s closing price—indicating severe liquidity pressures and an urgent need to raise capital amidst a hostile market environment.
Broader Market Performance: The Plunge of the Jakarta Composite Index
The distress experienced by Indonesia’s billionaire class is symptomatic of a wider malaise affecting the entire domestic capital market. The Jakarta Composite Index (IHSG) has suffered a brutal contraction, plunging 38% throughout the year. Comparative global financial data compiled by Bloomberg underscores the severity of this domestic correction: the Indonesian benchmark index has recorded the worst performance among more than 90 major global equity indices monitored internationally.
This dramatic underperformance has alarmed local regulators, institutional investors, and retail participants alike. The mass exodus of foreign capital, combined with forced liquidations and margin calls among domestic investors, has created a negative feedback loop, depressing price-to-earnings multiples across nearly all major sectors, including banking, consumer goods, mining, and basic materials.
Official Responses and Sovereign Defiance
As market anxiety reached a boiling point, high-ranking government officials intervened to project national resilience and address the regulatory standoff with international institutions. In response to the escalating crisis and the looming threat from MSCI, President Prabowo Subianto issued a sharp and unyielding message. In remarks that reverberated across financial circles, the Indonesian leadership made it unequivocally clear that the nation refuses to bow to external pressure.
"Indonesia does not fear anyone!" stood as the core message conveyed to index providers and foreign market critics. Government representatives emphasized that the country’s macroeconomic fundamentals remain robust, pointing to stable economic growth, controlled inflation, and strong banking sector capital adequacy ratios as proof that the stock market sell-off is disconnected from the broader real economy. State officials have held emergency consultations with the Indonesia Stock Exchange (IDX) and the Financial Services Authority (OJK) to formulate stabilization strategies, restore investor confidence, and evaluate potential regulatory adjustments to enhance market transparency and liquidity.
Implications for the Indonesian Economy and Future Outlook
The wiping out of IDR 1,033 trillion in billionaire wealth carries profound implications for the Indonesian economy, corporate governance, and capital market development. While analysts like Layenda Kresna Bramanta emphasize that much of the lost capital is theoretical "paper wealth," the psychological and practical impacts on corporate behavior are undeniable.
First, the crisis exposes the inherent risks of concentrated family ownership in major Indonesian corporations. When controlling shareholders face liquidity squeezes or margin pressures, forced sales of large blocks of shares can distort pricing mechanisms and trigger cascading sell-offs across the broader market. This dynamic underscores the urgent need for local conglomerates to broaden their free-float percentages and enhance institutional governance to attract more resilient, long-term capital.
Second, the episode serves as a severe wake-up call for Indonesian regulators regarding compliance with global financial standards. Maintaining international market credibility requires continuous alignment with transparency, governance, and liquidity benchmarks established by global arbiters like MSCI. Failure to address these structural concerns risks deepening the country’s isolation from major global benchmark funds, potentially raising the cost of capital for Indonesian corporations seeking international financing.
Finally, the long-term recovery of the Jakarta Composite Index will depend heavily on restoring foreign investor confidence through transparent regulatory reforms, consistent policy implementation, and continued fiscal discipline by the administration. As Indonesia navigates this turbulent transition, the resilience of its domestic economy—supported by strong domestic consumption and strategic infrastructure investments—will serve as the primary bulwark against external financial pressures. The events of 2026 will undoubtedly be studied for years to come as a watershed moment that reshaped the landscape of Indonesian corporate wealth and capital market governance.
