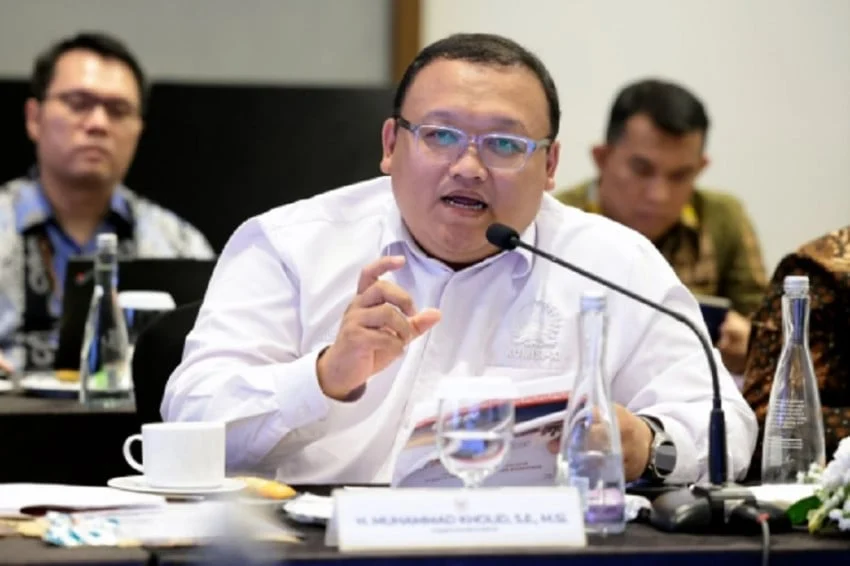
The debate surrounding the future of Indonesia’s fiscal architecture has intensified as the government and legislature deliberate on the proposed revisions to Law Number 17 of 2003 concerning State Finances. At the heart of this legislative tension is a proposal to potentially loosen the long-standing budget deficit cap, which currently limits the annual state budget deficit to a maximum of 3 percent of the Gross Domestic Product (GDP). Muhammad Kholid, a prominent member of Commission XI of the House of Representatives (DPR) representing the Prosperous Justice Party (PKS), has emerged as a vocal critic of this move, arguing that maintaining the 3 percent ceiling is non-negotiable to ensure the nation’s long-term fiscal health and international credibility.
The Historical Context of the 3 Percent Cap
To understand the weight of Kholid’s objection, one must look back at the origins of the 3 percent deficit rule. Introduced in the aftermath of the 1997-1998 Asian Financial Crisis, the provision was embedded in the 2003 State Finance Law as a safeguard against reckless fiscal expansion. During the crisis, Indonesia’s debt-to-GDP ratio ballooned, and the economy suffered from hyperinflation and currency collapse. The rule served as a "fiscal anchor," providing a clear signal to international investors, credit rating agencies, and multilateral institutions—such as the International Monetary Fund (IMF) and the World Bank—that Indonesia was committed to disciplined, sustainable economic governance.
For over two decades, this limit has been the bedrock of Indonesia’s fiscal policy. While the government temporarily suspended this rule during the height of the COVID-19 pandemic—allowing the deficit to widen beyond 3 percent in 2020, 2021, and 2022 to fund emergency social safety nets and healthcare expenditures—the return to the 3 percent threshold has been a hallmark of Indonesia’s post-pandemic fiscal consolidation strategy.
The Legislative Push for Flexibility
The current discussion regarding the revision of Law No. 17/2003 is framed by the government’s desire for greater agility. Proponents of lifting the cap argue that in an increasingly volatile global economic landscape, rigid adherence to a 3 percent deficit limit may restrict the state’s ability to fund transformative national projects, such as infrastructure development, energy transition initiatives, and the pursuit of "Golden Indonesia 2045" objectives.
Supporters of the revision contend that the quality of spending—rather than the sheer size of the deficit—is what determines economic success. They argue that if a higher deficit is utilized for high-multiplier projects, it will eventually pay for itself through expanded tax bases and increased economic productivity. However, this view is met with skepticism by members of the opposition, who fear that removing or relaxing the ceiling could lead to undisciplined spending and a dangerous accumulation of debt.
PKS Stance: Safeguarding Fiscal Credibility
Muhammad Kholid’s opposition is rooted in the principle of "fiscal prudence." Speaking to the press on September 20, 2026, Kholid acknowledged that the government’s ambition to accelerate economic growth is a noble and necessary objective. However, he emphasized that such growth must not come at the expense of macroeconomic stability.
"We share the same vision of driving higher economic growth. However, we believe the 3 percent cap is still the most appropriate benchmark for controlling state debt and maintaining the credibility of our fiscal policies," Kholid stated. According to the PKS legislator, the 3 percent threshold acts as a psychological and structural barrier that forces the government to prioritize efficient spending and maximize revenue collection. He argues that once this barrier is removed, the political temptation to expand the deficit during election cycles or periods of low revenue would be difficult to curb, potentially leading to a "fiscal cliff" scenario.
Analyzing the Economic Implications
The debate over the deficit cap is not merely a technical disagreement; it has profound implications for Indonesia’s sovereign credit rating and the cost of borrowing. International rating agencies, including Moody’s, Fitch, and S&P, monitor Indonesia’s fiscal stance closely. A commitment to fiscal discipline has been a key factor in Indonesia maintaining its investment-grade status, which in turn keeps government bond yields at manageable levels.

If the 3 percent cap were to be abandoned or significantly altered, there is a risk that investors might perceive this as a signal of weakening fiscal discipline. Should investors demand higher premiums to hold Indonesian government securities, the interest burden on the state budget—already a significant portion of national expenditure—would rise, effectively crowding out essential spending on health, education, and infrastructure.
Furthermore, economic analysts point out that Indonesia’s tax-to-GDP ratio remains relatively low compared to regional peers. Critics of the government’s push to loosen the deficit cap argue that before discussing higher deficits, the government should prioritize tax reform and administrative efficiency. By expanding the tax base and reducing illicit financial flows, the government could theoretically increase its fiscal space without needing to breach the 3 percent deficit threshold.
The Chronology of the Debate
The tension surrounding this revision has been brewing throughout 2026. Following the inauguration of new leadership and policy shifts, the government indicated a need to modernize the 2003 law to better suit modern challenges.
- Early 2026: Discussions began within the executive branch regarding the need to update the State Finance Law to accommodate new fiscal instruments.
- Mid-2026: The proposal was introduced to the legislative body, highlighting the need for "fiscal flexibility."
- Late Q3 2026: The discourse reached the public sphere, with Commission XI members expressing divergent views on the necessity of maintaining the 3 percent ceiling.
- September 20, 2026: Muhammad Kholid of PKS formally registers his dissent, bringing the issue to the forefront of national discourse.
Comparative Perspective: Global Standards
It is worth noting that while the 3 percent rule is a common benchmark globally—often associated with the Maastricht Treaty criteria in the European Union—many countries have adapted their rules to suit their specific economic stages. Some nations have moved toward "structural deficit" targets, which account for the economic cycle, rather than a hard numerical cap on the absolute deficit.
The challenge for Indonesia is to find a balance between the rigid rules of the past and the flexible needs of the future. The PKS argument, while conservative, resonates with a segment of the public and the financial community that values predictability and stability over high-risk growth models.
Future Outlook and Legislative Hurdles
As the revision process continues, the government faces a daunting task: building a consensus that satisfies the need for growth while reassuring stakeholders of Indonesia’s commitment to debt sustainability. The dialogue in the House of Representatives is expected to intensify in the coming weeks.
If the government insists on moving forward with the relaxation of the deficit limit, it will likely need to introduce a new, robust framework for fiscal accountability. This could include stricter oversight mechanisms, clear "escape clauses" that only trigger under specific, well-defined economic emergencies, and a mandatory path for medium-term fiscal consolidation.
Ultimately, the resolution of this debate will signal the trajectory of Indonesia’s economic policy for the next decade. Whether the 3 percent cap is preserved as a sacred guardian of fiscal integrity or replaced by a more flexible, perhaps more modern, fiscal framework, the priority remains the same: ensuring that the Indonesian state can fulfill its obligations to its citizens without compromising the nation’s financial sovereignty. As PKS and other stakeholders continue to weigh in, the focus will remain on the delicate balance between the aspiration for rapid development and the reality of the global financial order.