
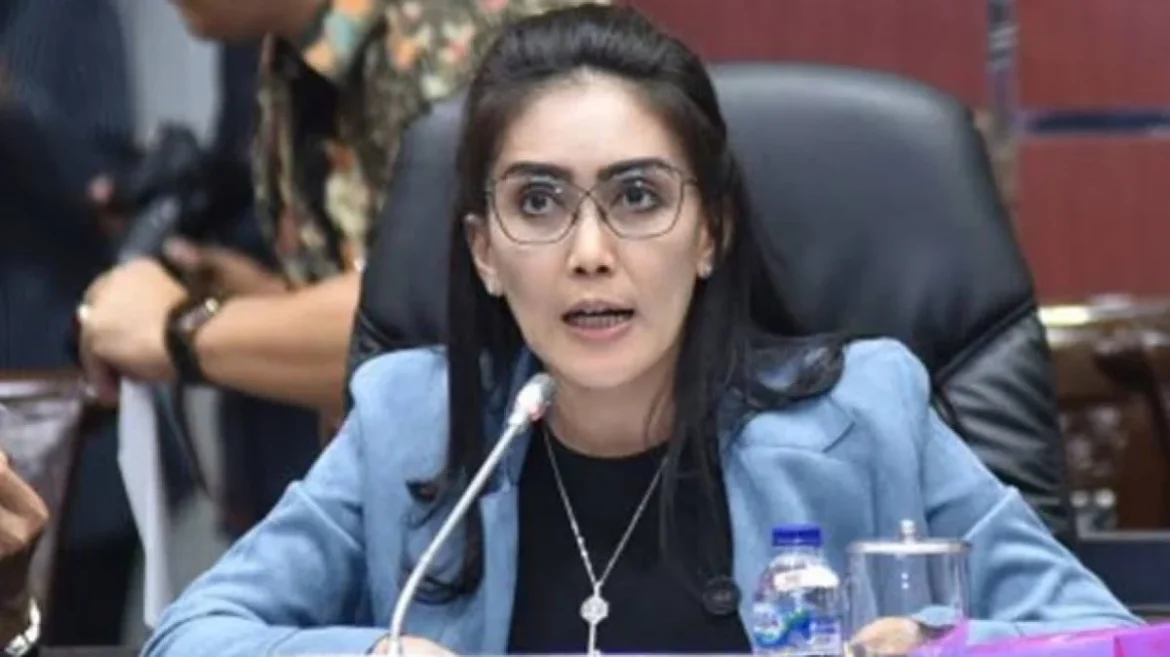
JAKARTA, Indonesia – Wednesday, October 22, 2025 – A recent incident involving the Pesantren Al-Fath Jalen in Tambun Utara, Kabupaten Bekasi, has ignited a national debate concerning the application of Property and Building Tax (PBB) on non-profit religious and educational institutions. The controversy erupted following an impassioned public outcry from Rieke Diah Pitaloka, a Member of Parliament (DPR RI) from the PDI Perjuangan faction, who vehemently protested against the tax demands leveled against the pesantren, founded by the late Kiai Yasin. Her emotional appeal, including a direct call to Minister of Finance Purbaya Yudhi Sadewa, has drawn widespread attention to the administrative complexities and potential injustices faced by institutions vital to Indonesia’s social and educational fabric.
The incident came to light through a video shared on Rieke Diah Pitaloka’s personal Instagram account, @riekediahp, under the banner "Viral for Justice" and the hashtag #SavePesantrenIndonesia. In the video, Rieke, visibly distressed during her visit to Pesantren Al-Fath Jalen, recounted the unexpected arrival of officials from the Regional Revenue Agency (Badan Pendapatan Daerah – Bapenda) to collect property taxes. Her exasperated plea, "Suddenly someone from the Regional Revenue Agency came to collect tax. Kang Purbaya, please, Kang Purbaya," underscored the urgency and perceived impropriety of the situation. She stressed that the foundation operating the pesantren was explicitly non-profit, stating, "My brother’s foundation doesn’t seek profit. How dare they collect taxes? We will resolve this according to legal customs."
The Plight of Pesantren Al-Fath: A Decade of Misinformation and Mounting Pressure
The administrator of Pesantren Al-Fath, Naili, provided a detailed chronology of events that led to the current predicament, highlighting a concerning gap in communication and understanding between government agencies and community institutions. According to Naili, the pesantren initially sought to formalize its land status through a wakaf (religious endowment) certificate around 2010. During this process, officials at the Office of Religious Affairs (Kantor Urusan Agama – KUA) explicitly informed them that as a pesantren, the institution would be exempt from PBB.
"Around 2010, we were processing the wakaf certificate through the KUA. The process was long and expensive. At that time, the KUA informed us that pesantren were exempt from PBB. As laypeople, we trusted that information," Naili explained during her interview with Rieke. This initial assurance formed the basis of their understanding for over a decade, leading them to believe their institution was not subject to property taxation.
However, this understanding was abruptly shattered in 2024 when Pesantren Al-Fath began receiving official tax bills. The situation escalated dramatically in 2025, when the pesantren received a dire warning that the property would be "police-lined," a term often implying administrative sealing or closure due to unpaid dues. "In 2025, we received a letter stating our pesantren would be police-lined. I cried, honestly. Not long after that, Abah [Kiai Yasin] passed away," Naili recounted, conveying the immense emotional and practical distress inflicted upon the community. The threat of closure not only jeopardized the educational continuity for its students but also deeply affected the morale of the community, especially in the wake of the founder’s passing.
Legal Framework: Exemptions for Non-Profit Public Interest Institutions
Rieke Diah Pitaloka’s strong stance is firmly rooted in existing Indonesian tax law, specifically citing Article 38 of the regulations concerning Property and Building Tax. This crucial article stipulates that PBB is not applicable to the ownership or utilization of land and buildings used solely for public interest purposes in the fields of religion, social welfare, health, education, and national culture, provided they are not intended for profit.
"A pesantren has effectively taken over the responsibility of the state. Things like this should certainly not happen," Rieke asserted, underscoring the vital role these institutions play in supplementing government efforts in education and social development. Pesantren, as traditional Islamic boarding schools, have historically been pillars of education and community development in Indonesia, often operating on minimal resources and relying on public donations and endowments. Their non-commercial nature is fundamental to their mission.
The legal basis for PBB in Indonesia originates from Law No. 12 of 1985 concerning PBB, subsequently amended by Law No. 12 of 1994. Crucially, with the enactment of Law No. 28 of 2009 concerning Local Taxes and Retributions, the authority to manage and collect PBB (excluding PBB on mining, forestry, and plantation sectors) was decentralized to local governments. This decentralization aimed to empower regions to generate their own revenue but also introduced potential variations in implementation and interpretation at the local level. While the core national law provides for exemptions, local regulations are supposed to align with and further clarify these provisions.
Local Government Support and Acknowledged Administrative Gaps
Adding weight to Rieke’s argument, Nyumarno, a member of the Regional Legislative Council (DPRD) for Kabupaten Bekasi, who was present at Pesantren Al-Fath, corroborated the legal exemptions. He confirmed that local regulations in Kabupaten Bekasi indeed provide for tax exemptions for non-commercial places of worship and educational institutions.
"In Kabupaten Bekasi, there are indeed regulations stating that places of worship or non-commercial Islamic boarding schools can apply for PBB exemption," Nyumarno stated. However, he also pointed to a critical flaw in the practical application: "But in practice, tax bills often arrive without prior socialization." This admission highlights a systemic issue where administrative processes might be failing to adequately inform and process exemptions for eligible institutions, leading to undue burdens. Nyumarno pledged his direct assistance to Pesantren Al-Fath, committing to help them secure the PBB exemption. "For Pesantren Al-Fath, I will personally accompany them to ensure they are freed from PBB," he declared, offering a glimmer of hope for the distressed institution.
Broader Context: The Role and Challenges of Pesantren in Indonesia
Indonesia boasts a vast network of pesantren, numbering in the tens of thousands across the archipelago, serving millions of students. These institutions are not merely educational centers but also community hubs that preserve traditional Islamic values, foster moral development, and contribute to national character building. They often operate with limited funding, relying on community support, modest student fees, and endowments. The financial strain of unexpected tax burdens, especially those that are legally exempt, can severely jeopardize their existence and operational capacity.
The issue at Pesantren Al-Fath is not an isolated incident. Across Indonesia, many non-profit religious and educational institutions, including churches, temples, and schools, face similar bureaucratic hurdles and inconsistent application of tax laws. The decentralization of PBB has, in some instances, led to a more aggressive pursuit of local revenue targets by regional governments, sometimes at the expense of clear communication and adherence to exemption policies for vital social institutions. This creates an environment where institutions, often lacking dedicated legal or administrative staff, are vulnerable to misinterpretations or erroneous applications of tax regulations.
Furthermore, the concept of wakaf land, which Pesantren Al-Fath operates on, carries significant religious and legal weight. Wakaf is an Islamic endowment made by an individual or a group for charitable or religious purposes, typically involving land or buildings. The land is permanently dedicated and cannot be sold or inherited, with its benefits intended for the community. The legal framework surrounding wakaf properties is designed to protect their charitable intent, and thus, taxing such properties, especially when used for non-profit education, directly contradicts their fundamental purpose.
Implications for Tax Policy, Administrative Reform, and Social Justice
The case of Pesantren Al-Fath Jalen carries significant implications for national tax policy, administrative reform, and the broader discourse on social justice. First, it underscores the urgent need for enhanced socialization of tax laws, particularly concerning exemptions for non-profit entities. Regional Revenue Agencies must proactively engage with religious and educational institutions to ensure they are aware of their rights and the procedures for applying for exemptions, rather than waiting for disputes to arise.
Second, it calls for a review of internal administrative processes within Bapenda offices to prevent erroneous tax bills from being issued to legally exempt institutions. A robust verification system, perhaps linked with KUA data for wakaf properties or Ministry of Religious Affairs registries for pesantren, could prevent such incidents. The initial incorrect advice from KUA officials in 2010 also points to a need for better inter-agency coordination and consistent training for government personnel who interact with the public on property and tax matters.
Third, the strong intervention by a national legislator like Rieke Diah Pitaloka, and local support from DPRD member Nyumarno, highlights the critical role of political oversight in upholding justice and ensuring that bureaucratic processes serve the public good. Their actions send a clear message that legislative bodies are attentive to the challenges faced by grassroots institutions and are prepared to advocate for their rights.
Finally, at a higher level, the incident prompts a re-evaluation of the balance between local revenue generation and the state’s responsibility to support public interest institutions. While regional governments have legitimate needs for revenue, these must not come at the expense of institutions that provide essential services and contribute significantly to national development without seeking profit. The Minister of Finance, Purbaya Yudhi Sadewa, whom Rieke directly addressed, holds the ultimate authority to guide national tax policy and ensure that central directives regarding exemptions are clearly understood and consistently applied across all regional administrations. His office is expected to provide clarification and potentially issue directives to prevent similar occurrences nationwide.
Calls for Action and A Path Forward
The immediate resolution for Pesantren Al-Fath Jalen, with the promised direct assistance from DPRD member Nyumarno, is crucial. However, the broader challenge requires systemic solutions. There is a clear call for the Ministry of Finance and the Ministry of Home Affairs (which oversees regional governments) to collaborate on a comprehensive review of PBB implementation for non-profit religious and educational institutions. This review should aim to:
- Clarify and Standardize Procedures: Develop clear, easily accessible guidelines for non-profit institutions to apply for and maintain PBB exemptions.
- Improve Inter-Agency Data Sharing: Establish mechanisms for Bapenda, KUA, and the Ministry of Religious Affairs to share data on wakaf properties and registered non-profit institutions to prevent erroneous billing.
- Enhance Socialization and Education: Launch nationwide campaigns to educate both government officials and the public on PBB exemptions for public interest institutions.
- Strengthen Oversight: Implement robust oversight mechanisms to monitor regional PBB collection practices and ensure compliance with national exemption laws.
The passionate advocacy for Pesantren Al-Fath Jalen serves as a potent reminder of the ongoing need for vigilance in ensuring that laws designed to support public welfare are properly implemented. It highlights the often-unseen struggles of institutions that form the backbone of local communities and underscores the importance of a government that is responsive, transparent, and just in its administration of public policy. The outcome of this particular case will undoubtedly set a precedent and influence how similar situations are handled across Indonesia, ultimately shaping the relationship between the state and its vital non-profit sectors.
