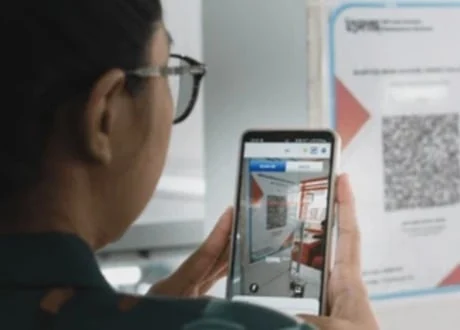
The landscape of retail and commercial transactions in Indonesia is undergoing a profound transformation, propelled by the relentless expansion of digital payment systems. At the heart of this financial evolution is the Quick Response Code Indonesian Standard (QRIS), a national interoperable QR code standard introduced by Bank Indonesia (BI) and the Indonesian Payment System Association (ASPI). As QRIS adoption penetrates deeper into the fabric of everyday commerce, businesses of all scales—from micro-enterprises to large retail chains—are rapidly re-engineering their financial infrastructures to accommodate a cashless consumer base. Recent data from the central bank underscores this monumental shift, revealing unprecedented milestones in both user acquisition and transaction volumes.
Amidst this broader macroeconomic trend, fintech providers and payment gateways are facing heightened competition to capture market share. Beyond merely offering competitive transaction fees, industry players are discovering that merchants increasingly demand comprehensive operational support, seamless onboarding experiences, and robust after-sales assistance. This dynamic was recently underscored by OttoDigital, a prominent digital payment ecosystem enabler in Indonesia, which emphasized that the modern merchant views a payment gateway not just as a transactional tool, but as an indispensable strategic partner in business growth.
The Exponential Growth of QRIS: Bank Indonesia’s Mid-2026 Data
Bank Indonesia’s statistical reports for the first half of 2026 illustrate the staggering velocity at which digital financial inclusion is progressing throughout the archipelago. According to central bank figures, the total number of registered QRIS users reached an impressive 65.77 million by June 2026. This metric reflects a massive demographic shift, as consumers across diverse socioeconomic strata embrace the convenience, speed, and safety of scanning-based digital payments.
Furthermore, the transactional activity utilizing the QRIS infrastructure has broken previous records. During the first semester of 2026 alone, cumulative transactions surged to an astonishing 12.55 billion events. In monetary terms, this volume translated into a staggering Rp1.12 kuadriliun (quadrillion rupiah), representing a dramatic year-on-year (yoy) growth rate of 93.92 percent. This explosive expansion highlights that QRIS is no longer merely an alternative payment method for urban millennials and tech-savvy consumers, but a primary medium of exchange embedded deeply within the national economy.
The economic implications of this growth are profound. The reduction of physical cash handling costs, enhanced transaction transparency, and improved cash flow management for merchants are among the primary macroeconomic benefits cited by financial analysts. However, this rapid scaling also introduces operational complexities, particularly for micro, small, and medium-sized enterprises (MSMEs) that may lack dedicated IT or finance departments to navigate technical glitches or compliance requirements.
Evolving Merchant Demands: Beyond Price Competition
As the digital payment ecosystem matures, the criteria by which business owners choose their payment service providers (PSPs) have shifted significantly. Historically, price wars characterized the fintech landscape, with various aggregators undercutting each other on MDR (Merchant Discount Rate) fees to attract business clients. While cost remains a critical factor for merchants operating on thin profit margins, qualitative factors have rapidly taken center stage.
In a recent official statement released on Friday, September 25, 2026, OttoDigital Chief Revenue Officer Grace Sunarjo articulated this evolving industry reality. Drawing from the company’s extensive operational history, Sunarjo highlighted the insights gained from nearly a decade of serving thousands of merchants across diverse commercial sectors.
"OttoPay’s experience serving thousands of merchants for nearly a decade proves that business owners need more than just a payment gateway provider with competitive pricing. They need a payment partner with the best service," stated Grace Sunarjo.
Sunarjo elaborated that modern business owners face daily operational pressures that extend far beyond transaction processing fees. Key pain points often include cumbersome administrative verification processes, delayed onboarding timelines, opaque dispute resolution mechanisms, and a lack of responsive technical support when payment terminals or application interfaces experience downtime. As businesses grow increasingly dependent on non-digital alternatives becoming obsolete, any friction in the digital payment pipeline translates directly into lost revenue and diminished customer satisfaction.
Streamlining Onboarding: The Operational Response to Merchant Needs
Recognizing the critical bottlenecks that hinder business digitization, payment service providers are racing to optimize their operational workflows. A primary hurdle for many MSMEs historically has been the bureaucratic friction involved in document verification and account activation. Lengthy onboarding procedures can discourage traditional merchants from transitioning to digital platforms, delaying their integration into the formal digital economy.
In response to these industry-wide challenges, OttoDigital—through its merchant-focused service arm, OttoPay—has implemented accelerated operational protocols. The company announced that its QRIS activation process can now be completed within a strict window of three working days, provided that all required documentation from the prospective partner has been successfully verified.
This expedited timeline is strategically designed to mitigate the initial barriers to entry for business owners. By shortening the span between application and operational readiness, OttoPay aims to enable merchants to commence digital transactions swiftly, thereby capturing consumer demand without unnecessary delays.
"Our commitment to providing the best service is presented from the early stages, through a practical registration process to after-sales assistance," Sunarjo added, emphasizing that technical and administrative hand-holding is crucial for long-term merchant retention and satisfaction.
The Regulatory Landscape and Coexistence of Cash
While the push toward a cashless society is championed by both regulatory bodies and private fintech firms, Bank Indonesia maintains a balanced approach to ensure financial inclusivity across all demographics. Concurrently with the promotion of QRIS, the central bank has issued clear directives regarding the status of physical currency within the national financial system.
Recent regulatory reminders from Bank Indonesia emphasize that while merchants are strongly encouraged—and in many digital-first ecosystems practically required—to adopt QRIS and other electronic payment formats, they are legally prohibited from outright rejecting physical cash as a legitimate tender. This policy is designed to protect vulnerable segments of the population, such as the elderly or individuals in remote areas with limited internet infrastructure, ensuring they are not disenfranchised by the rapid digitization of commerce.
The coexistence of robust digital infrastructure like QRIS alongside traditional cash creates a hybrid economic environment. For merchants, this means managing dual-channel liquidity: maintaining efficient reconciliation processes for digital ledger inflows while ensuring secure handling and banking of physical cash reserves. Consequently, payment partners that offer integrated reporting dashboards—combining both QRIS and cash transaction logs into a single interface—are gaining a distinct competitive advantage in the market.
Macroeconomic Implications and the Path Forward
The trajectory of QRIS adoption through mid-2026 offers a clear window into the future of Indonesia’s digital economy. Surpassing 65 million users and crossing the milestone of Rp1.12 kuadriliun in six-month transaction value demonstrates that the national digital payment framework has achieved critical mass.
However, sustaining this momentum requires continuous collaboration between regulators, financial institutions, and fintech enablers. As cyber security threats evolve, maintaining consumer trust through robust data protection measures remains paramount. Simultaneously, continuous education initiatives are required to onboard the remaining segments of the informal economy into the QRIS ecosystem.
For fintech players like OttoDigital, the challenge moving forward will lie in scalability and service differentiation. As basic QRIS integration becomes a commoditized feature available across almost every financial application, value-added services—such as integrated inventory management, automated bookkeeping, micro-lending access based on transaction history, and superior customer support—will dictate market leadership.
Ultimately, the ongoing expansion of QRIS is reshaping the commercial DNA of Indonesia. By bridging the gap between technological capability and merchant-centric operational support, the ecosystem is laying a resilient foundation for sustainable economic growth, financial inclusion, and enhanced business efficiency in the years to come.