Jakarta, Indonesia – October 22, 2025 – A significant controversy has erupted following the revelation that Pesantren Al-Fath Jalen, a revered Islamic boarding school in Tambun Utara, Kabupaten Bekasi, has been issued substantial property tax (Pajak Bumi dan Bangunan – PBB) bills, despite legal provisions typically exempting non-profit religious and educational institutions. The issue gained widespread attention after Member of Parliament Rieke Diah Pitaloka, representing the PDI Perjuangan faction in Commission VI of the House of Representatives (DPR RI), publicly voiced her vehement objection, even directly appealing to Minister of Finance Purbaya Yudhi Sadewa for intervention. This incident has ignited a broader discussion on the implementation of tax regulations for non-profit entities, particularly those serving critical public functions.
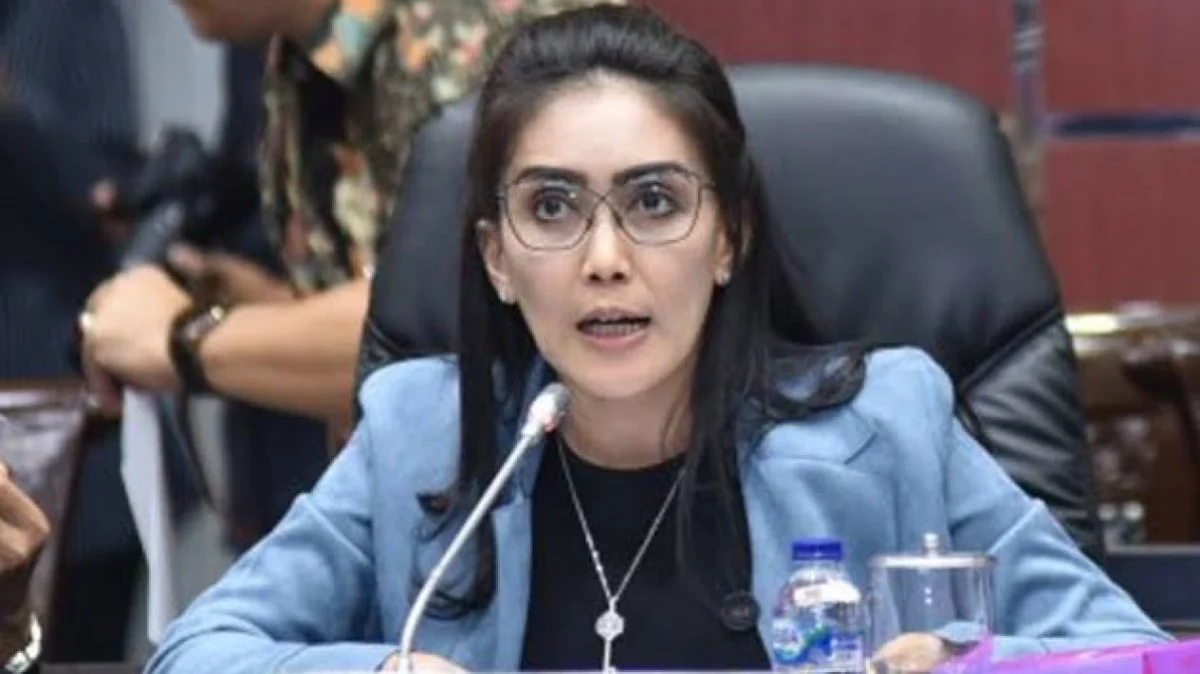
The controversy unfolded when Rieke Diah Pitaloka, a prominent figure known for her advocacy in social justice and labor rights, shared an emotional video on her personal Instagram account, @riekediahp, under the banner "Viral for Justice" and the hashtag #SavePesantrenIndonesia. In the video, filmed during her visit to Pesantren Al-Fath Jalen, the lawmaker expressed profound dismay and anger upon learning of the tax demands. Her frustration was palpable as she recounted how officials from the local Regional Revenue Agency (Badan Pendapatan Daerah – Bapenda) had visited the pesantren to collect the property tax. "Suddenly, people came from the Regional Revenue Agency demanding tax. Kang Purbaya, please, Kang Purbaya!" Rieke exclaimed, her voice filled with urgency and disbelief, directly addressing the Minister of Finance. Her impassioned plea underscored the perceived injustice of the situation, particularly given the pesantren’s role as a non-profit educational institution.
The Pesantren at the Heart of the Dispute: Al-Fath Jalen
Pesantren Al-Fath Jalen, established by the late Kiai Yasin, has long served as a pillar of religious education and community development in Tambun Utara, Bekasi. Like thousands of other pesantren across Indonesia, it operates primarily as a non-profit institution dedicated to providing Islamic education, character building, and social services. These institutions often function as extensions of the state’s educational and social welfare responsibilities, particularly in remote or underserved areas, contributing significantly to national human resource development without seeking commercial gain. The financial sustainability of such institutions typically relies on donations, endowments (waqf), and community support, rather than revenue generation from commercial activities. The land and buildings upon which Pesantren Al-Fath Jalen stands are understood to be waqf property, meaning they are endowed for charitable or religious purposes, further reinforcing their non-commercial status.
The management of Pesantren Al-Fath Jalen, represented by Naili, detailed a perplexing chronology of events that led to the current predicament. According to Naili, when the pesantren initiated the process of obtaining a waqf certificate for its land and buildings around 2010, officials at the local Office of Religious Affairs (Kantor Urusan Agama – KUA) explicitly informed them that pesantren, by their very nature and waqf status, were exempt from PBB. "Around 2010, we processed the waqf certificate at the KUA. The process was lengthy and expensive. At that time, KUA officials told us that pesantren were exempt from PBB. As ordinary people, we simply believed them," Naili recounted during her interview with Rieke Diah Pitaloka. This initial assurance, coming from a government agency involved in religious affairs, formed the basis of the pesantren’s understanding regarding its tax obligations, or rather, its lack thereof.
For over a decade, the pesantren operated under this premise, focusing its limited resources on its educational and religious mission, serving hundreds of students from the surrounding communities. However, the situation dramatically changed in 2024 when the first property tax bills began arriving, catching the pesantren management completely by surprise. The surprise turned to alarm in 2025 when the pesantren received a more ominous letter, threatening a "police line" – a term often associated with the sealing or seizure of property for non-payment of taxes or legal violations. "In 2025, we received a letter stating that our pesantren would be ‘police-lined.’ I cried, honestly. Not long after that, Abah (Kiai Yasin) passed away," Naili shared, highlighting the immense stress and emotional toll these demands have taken on the pesantren community, particularly in the wake of their founder’s passing. The threat of property seizure, even if administrative, carries significant psychological weight and could severely disrupt the operations of an institution vital to its community, potentially displacing students and staff.
The Legal Basis for Exemption: A Deep Dive into Indonesian PBB Regulations
Rieke Diah Pitaloka’s vehement objection is rooted in a specific legal provision, namely Article 38 of the regulations governing Property and Building Tax (Pajak Bumi dan Bangunan). While the original source refers to "Article 38 in the regulation regarding PBB," it’s crucial to contextualize this within Indonesia’s broader tax framework. The primary legislation governing property tax in Indonesia has evolved, with the responsibility for PBB-P2 (Pajak Bumi dan Bangunan Perdesaan dan Perkotaan, or Rural and Urban Land and Building Tax) largely devolved to local governments under Law No. 28 of 2009 concerning Regional Taxes and Regional Levies (Undang-Undang Pajak Daerah dan Retribusi Daerah). Subsequent legislation, such as Law No. 1 of 2022 concerning Financial Relations between the Central Government and Regional Governments, further clarifies these responsibilities, giving local Bapenda agencies the authority to collect PBB-P2.
Crucially, Article 77 of Law No. 28 of 2009 (and similar provisions in previous PBB laws, such as Law No. 12 of 1985 as amended by Law No. 12 of 1994) outlines specific exemptions for PBB. These exemptions typically apply to land and buildings that are used solely for public interest purposes in the fields of religion, social welfare, health, education, and national culture, provided they are not intended to generate profit. This is precisely the clause that Rieke Diah Pitaloka invoked, arguing that Pesantren Al-Fath Jalen perfectly fits this description.
"My brother’s foundation (referring to the pesantren’s underlying legal entity) doesn’t seek profit. How dare they demand tax? We will resolve this according to customary law, I mean, legal custom," Rieke asserted, underscoring her belief that the tax demand directly contradicts the spirit and letter of the law. She further emphasized, "Pesantren have already taken over the responsibilities of the state. Things like this certainly shouldn’t happen." Her argument highlights the dual role of pesantren as private institutions that nonetheless fulfill public functions, thereby deserving state support and, crucially, tax exemptions as a form of indirect subsidy. This principle is not unique to Indonesia; many countries offer similar tax benefits to non-profit charitable, religious, and educational organizations, recognizing their societal contributions.
Local Government Perspective and Pledges of Support
Adding significant weight to Rieke’s argument, Nyumarno, a member of the Regional House of Representatives (DPRD) for Kabupaten Bekasi, who was also present during Rieke’s visit, corroborated the existence of local regulations supporting the exemption of pesantren from PBB. "In Kabupaten Bekasi, there is indeed a regulation that places of worship or non-commercial Islamic boarding schools can be proposed for PBB exemption," Nyumarno stated. This confirms that the principle of exemption for such institutions is not merely a central government policy but is also enshrined in local ordinances, reflecting a consistent policy direction across different levels of government.
Nyumarno, however, acknowledged a critical flaw in the implementation: the lack of proper socialization of these regulations and the administrative processes required to secure such exemptions. "But in practice, there are indeed bills that arrive without prior socialization," he admitted. This points to a systemic issue where the letter of the law and its practical execution diverge, leading to confusion and distress for institutions like Pesantren Al-Fath Jalen. Recognizing the distress caused to the pesantren, Nyumarno pledged direct assistance: "For Pesantren Al-Fath, I will personally accompany them to ensure they are exempted from PBB." This commitment from a local legislator offers a glimmer of hope for the pesantren and underscores the immediate need for better communication and administrative clarity between local tax authorities and the public they serve.
Broader Implications: Pesantren’s Role and Administrative Challenges
This incident at Pesantren Al-Fath Jalen is not an isolated case but rather a microcosm of potential systemic issues concerning tax administration for non-profit organizations in Indonesia. Indonesia boasts a vast network of over 30,000 pesantren, educating millions of students annually and contributing immensely to the nation’s social fabric and religious harmony. These institutions are integral to Indonesia’s unique educational landscape, often providing holistic learning that encompasses religious studies, general knowledge, and vocational skills. The government, through various ministries like the Ministry of Religious Affairs, frequently provides grants and support programs to pesantren, acknowledging their vital role in national development and character building. Demanding PBB from institutions that are explicitly designed to be non-profit and serve public interests can directly contradict broader government policy aimed at strengthening these educational centers.
The administrative burden for small, community-run institutions like Pesantren Al-Fath Jalen in navigating complex tax bureaucracy is significant. The initial advice from the KUA in 2010, while perhaps well-intentioned, highlights a potential disconnect or lack of clarity regarding the precise procedures for claiming PBB exemption. While the spirit of the law intends to exempt such entities, the practical application often requires specific applications, documentation, and periodic re-verification processes that might not be easily understood or accessible to non-specialists. Many pesantren, especially those in rural areas or with limited administrative capacity, may struggle to keep abreast of evolving tax regulations or to fulfill intricate bureaucratic requirements. The sudden arrival of bills and threats of "police lines" without prior engagement or clear explanation of the administrative process for exemption can be deeply unsettling and counterproductive, potentially diverting precious resources from their core educational mission to dispute tax claims.
Potential Responses and Future Steps
The public outcry from a prominent lawmaker like Rieke Diah Pitaloka is likely to prompt a response from various government bodies.
- Ministry of Finance/Directorate General of Taxes: While PBB-P2 is a local tax, the Ministry of Finance, as the central authority for fiscal policy, may issue a statement emphasizing the importance of applying tax laws fairly and supporting non-profit institutions. They might reiterate national guidelines for exemptions and urge local governments to review their administrative processes to ensure consistency and transparency. They could also underscore the central government’s commitment to ensuring that tax policies do not inadvertently burden institutions critical for public welfare and national education.
- Local Revenue Agency (Bapenda) Kabupaten Bekasi: Bapenda will likely need to conduct a thorough and expedited review of Pesantren Al-Fath Jalen’s case. This would involve verifying its non-profit status, its use of the property for exclusively religious and educational purposes, and the historical records of its waqf certification. Should an administrative error or misclassification be confirmed, the agency would be expected to offer a waiver or cancellation of the past due bills. Furthermore, the agency would be expected to address the concerns about lack of socialization of tax regulations and exemption procedures, perhaps by initiating proactive outreach programs for religious and educational institutions.
- Ministry of Religious Affairs: The Ministry could play a crucial mediating and clarifying role, especially given the initial advice provided by the KUA. They might issue circulars or clearer guidelines to KUA offices nationwide regarding their role in informing religious institutions about tax exemptions and the administrative steps involved. This would help prevent future misunderstandings and ensure that accurate information is consistently provided across all levels.
Expert Perspectives on Tax Administration for Non-Profits
Tax experts often point to the complexities of property tax administration, particularly when dealing with non-profit entities. "The challenge often lies in verifying the actual non-profit status and ensuring the property is exclusively used for the stated exempt purposes," notes Dr. Sari Dewi, a tax law specialist from a prominent Indonesian university. "While the law is clear, administrative lapses can occur due to data discrepancies, changes in property use over time, or simply a lack of effective communication channels between tax authorities and the institutions they oversee. A proactive approach from local governments, including regular outreach and clear guidance for exemption applications, is crucial. The onus shouldn’t always be on the non-profit to navigate complex bureaucratic hurdles; the government also has a responsibility to facilitate legal exemptions."
Legal experts would also emphasize the importance of administrative appeal mechanisms. Institutions wrongly billed have the right to challenge these assessments through formal channels, a process often involving submitting objections and appeals. However, for many small institutions, navigating these legal complexities without assistance can be daunting, highlighting the value of intervention from public figures like Rieke Diah Pitaloka and local representatives like Nyumarno, who can provide direct support and amplify the issue.
Conclusion: Upholding the Spirit of the Law
The incident involving Pesantren Al-Fath Jalen serves as a poignant reminder of the delicate balance between efficient tax collection and the promotion of public welfare. While robust tax collection is essential for national and local development, it must be administered with fairness, clarity, and strict adherence to the spirit of laws designed to support vital social and educational institutions. The emotional plea from Rieke Diah Pitaloka and the distress experienced by the pesantren management underscore the very real human impact of administrative errors or ambiguities in policy implementation.
As Indonesia continues to develop, ensuring that institutions like pesantren can operate without undue financial burden, consistent with their legal exemptions, is paramount. This case calls for a comprehensive review of PBB implementation for non-profit entities nationwide, improved coordination among central and local government agencies, and enhanced efforts to educate both tax collectors and the public on existing tax regulations and exemption procedures. Ultimately, upholding the spirit of the law means protecting the institutions that contribute tirelessly to the nation’s social, educational, and spiritual well-being. The swift and just resolution of Pesantren Al-Fath Jalen’s predicament will be a critical test of the government’s commitment to these fundamental principles.