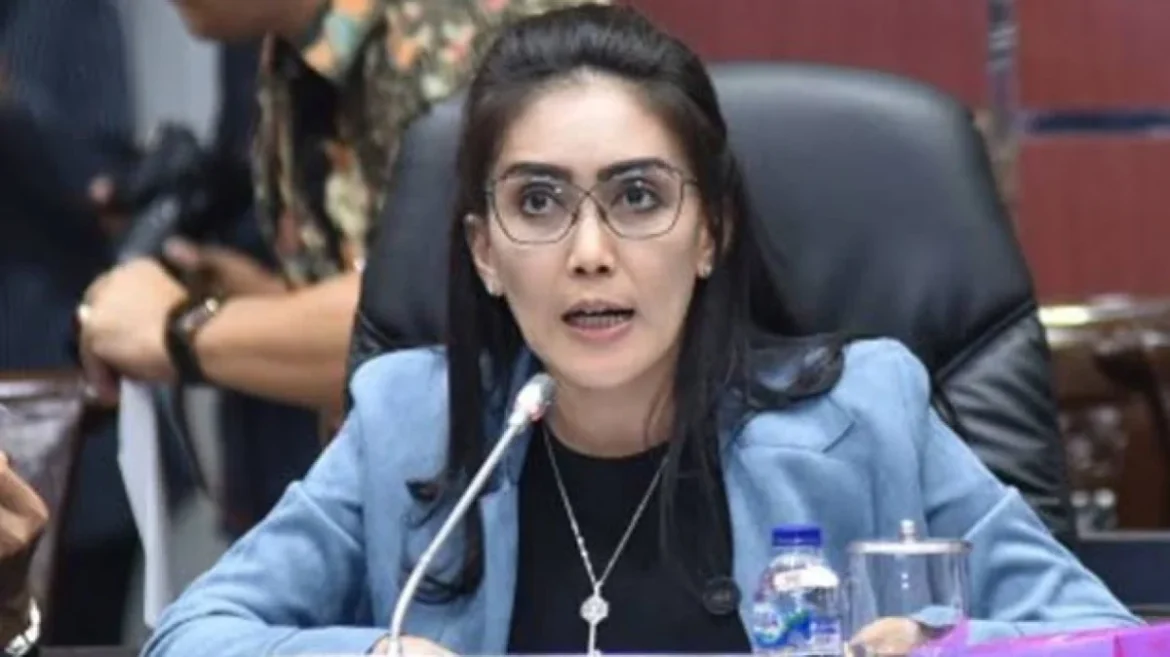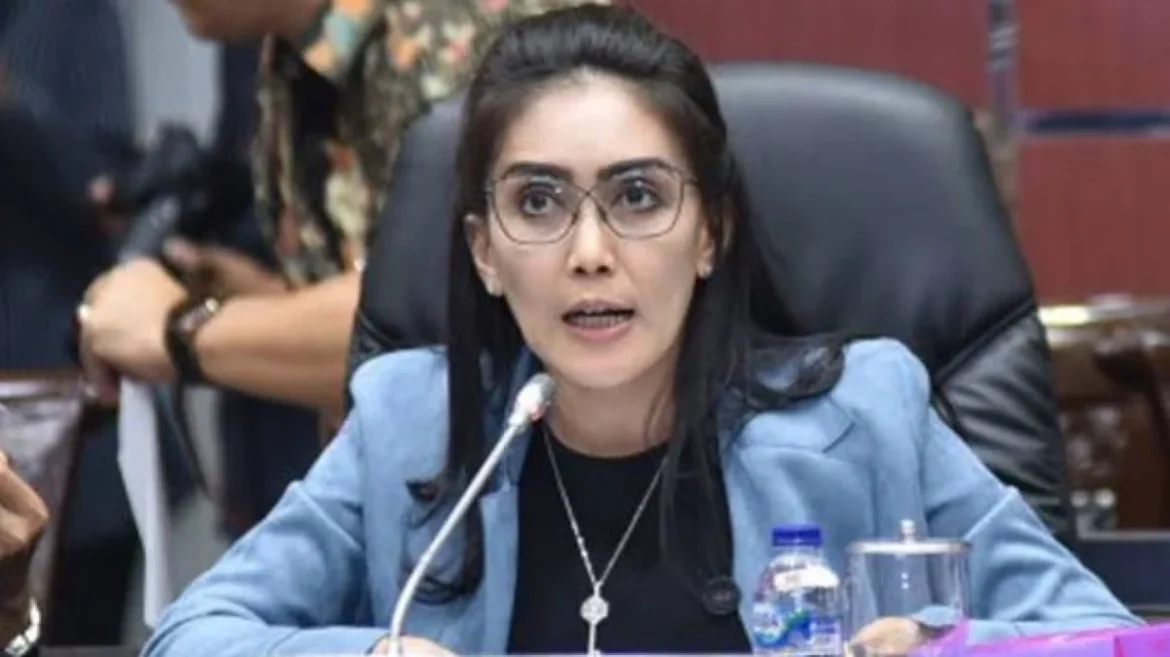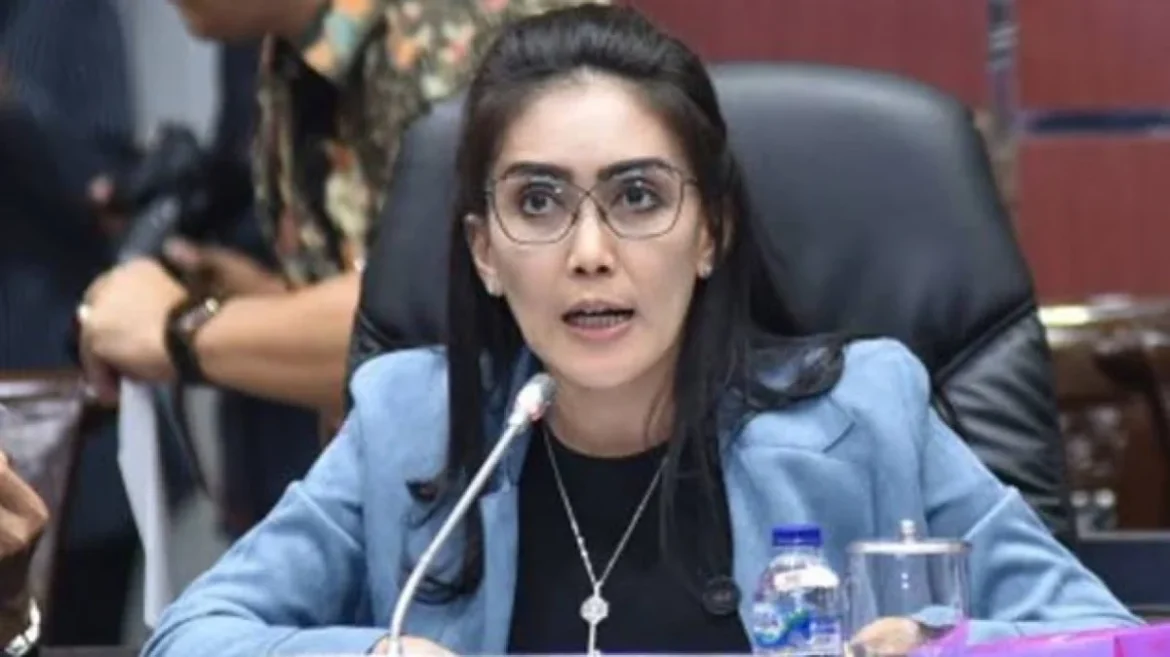
The intersection of taxation policy and religious educational institutions in Indonesia became a focal point of intense public discussion following a viral incident involving high-ranking government officials and local community leaders. Rieke Diah Pitaloka, a member of Commission VI of the House of Representatives (DPR RI) representing the Indonesian Democratic Party of Struggle (PDI-P), expressed profound indignation upon discovering that a local Islamic boarding school, or pesantren, founded by the late Kiai Yasin, was subjected to billing for the Land and Building Tax (Pajak Bumi dan Bangunan or PBB). The incident unfolded at Pesantren Al-Fath Jalen, located in Tambun Utara, Bekasi Regency, West Java.
The event quickly captured national attention after Rieke documented her visit to the institution and shared the footage on her official Instagram account, @riekediahp, under the digital campaign banner of Viral for Justice and the hashtag #SavePesantrenIndonesia. In the video, which circulated widely across various social media platforms, the lawmaker raised her voice in direct appeal to Finance Minister Purbaya Yudhi Sadewa, questioning the rationale behind imposing municipal property taxes on a non-profit religious and educational sanctuary that serves the local community.
Chronology of Events and the Origin of the Tax Dispute
The controversy surrounding Pesantren Al-Fath Jalen stems from a long-standing misunderstanding regarding administrative procedures, legal exemptions, and communication between local government tax agencies and religious institutions. According to Naili, an administrator at Pesantren Al-Fath, the institution’s journey with land administration began around 2010 when the management approached the local Office of Religious Affairs (KUA) to secure official waqf (endowment) land certificates.
During the initial processing phase, administrators were informed that the procedures were both lengthy and costly. However, representatives from the KUA reportedly assured the school management that because it was a registered religious and educational institution, the property would be permanently exempted from the Land and Building Tax (PBB). Given their status as laypeople unfamiliar with complex municipal tax codes, the pesantren administrators relied on this guidance and proceeded without seeking further formal tax clearances from local revenue offices.
For over a decade, the institution operated without major administrative hurdles regarding taxation. However, the situation shifted dramatically in 2024 when the management began receiving formal tax payment notices from the regional revenue office. The pressure escalated significantly in early 2025 when the administration was confronted with threats of formal asset seizure, including the potential application of police lines around the school premises due to accumulated unpaid taxes. Naili recounted that the mounting pressure severely distressed the founder, the late Kiai Yasin, who passed away shortly after the threats of legal action were communicated to the school.
Legal Framework Governing Tax Exemptions for Educational and Religious Institutions
The core argument presented by Rieke Diah Pitaloka and local officials rests on established legal provisions concerning tax exemptions for public interest properties in Indonesia. Rieke explicitly referenced Article 38 of the prevailing regulatory framework concerning the Land and Building Tax. Under this provision, tax obligations do not apply to the ownership, acquisition, or utilization of land and buildings dedicated exclusively to public interests in the fields of religion, social welfare, health, national education, and culture, provided that these properties are not operated for commercial gain or profit generation.
Pesantren Al-Fath Jalen, like thousands of similar traditional Islamic boarding schools across the archipelago, operates as a non-profit foundation. These institutions traditionally rely on donations, community support, and modest contributions to provide lodging, religious instruction, and general education to underprivileged youths.
During her inspection of the premises, Rieke emphasized the vital socio-educational role that pesantrens play in Indonesian society, arguing that they effectively absorb responsibilities that otherwise fall squarely on the state’s shoulders. By providing housing, moral guidance, and education to generations of students, these institutions contribute directly to national human resource development. Consequently, imposing commercial-style property taxes on such establishments contradicts both the letter of the law and the broader social contract between the state and educational pioneers.
Local Government Response and Remedial Actions
The urgency of the situation prompted immediate local legislative intervention. Nyumarno, a member of the Bekasi Regency Regional House of Representatives (DPRD) who accompanied Rieke during the site visit, acknowledged the administrative lapse and confirmed that local municipal regulations explicitly exempt places of worship and non-commercial educational institutions from PBB liabilities.
Nyumarno explained that while the legal mechanisms for tax exemption exist within the regional statutes of Bekasi Regency, the implementation often suffers from bureaucratic disconnects and a lack of proactive outreach. In many cases, tax assessments are generated automatically through systemic updates by local revenue agencies without cross-referencing zoning records or verifying the non-profit status of specific parcels of land. This systemic oversight frequently results in automated billing notices being sent to religious and educational entities that are legally entitled to exemptions.
Addressing the media and the school administrators on-site, Nyumarno committed to providing direct legal and administrative assistance to resolve the status of Pesantren Al-Fath Jalen. He assured the management that local legislative oversight would be utilized to cancel the outstanding tax bills, lift any pending administrative sanctions, and officially register the institution under the permanent tax-exempt database of Bekasi Regency. Furthermore, local authorities pledged to review broader notification protocols to prevent similar incidents from affecting other religious and educational foundations in the region.
Broader Implications for Tax Administration and Public Trust
The incident at Pesantren Al-Fath Jalen highlights broader systemic challenges within Indonesia’s decentralized fiscal administration. Following regional autonomy laws, local governments rely heavily on local taxes, such as the Land and Building Tax (PBB) and Motor Vehicle Tax, to generate regional original revenue (Pendapatan Asli Daerah or PAD). In their efforts to maximize revenue collection targets, regional revenue agencies (Bapenda) occasionally utilize automated data systems that flag idle or under-documented land parcels without conducting thorough preliminary field verifications.
This administrative push for revenue enhancement, when decoupled from rigorous social mapping and inter-agency coordination, risks alienating community stakeholders and undermining public trust in municipal governance. When non-profit religious and educational institutions—which hold immense cultural and social authority in Indonesia—are subjected to aggressive tax collection tactics, it frequently triggers swift public backlashes, as demonstrated by the viral nature of Rieke Diah Pitaloka’s social media intervention.
Experts in public policy note that incidents of this nature underscore the urgent need for enhanced integration between regional tax databases, the Ministry of Religious Affairs registry, and local civil administration records. Ensuring that properties dedicated to waqf, religious worship, and foundational education are systematically flagged at the point of land titling can permanently eliminate the risk of erroneous tax assessments.
As public scrutiny remains focused on the response from the Ministry of Finance and local tax authorities in Bekasi, the case of Pesantren Al-Fath Jalen serves as a cautionary tale regarding bureaucratic oversight. It highlights the necessity of administrative empathy and precision when implementing fiscal policies, ensuring that grassroots institutions dedicated to public education and religious welfare are safeguarded rather than burdened by state taxation mechanisms.