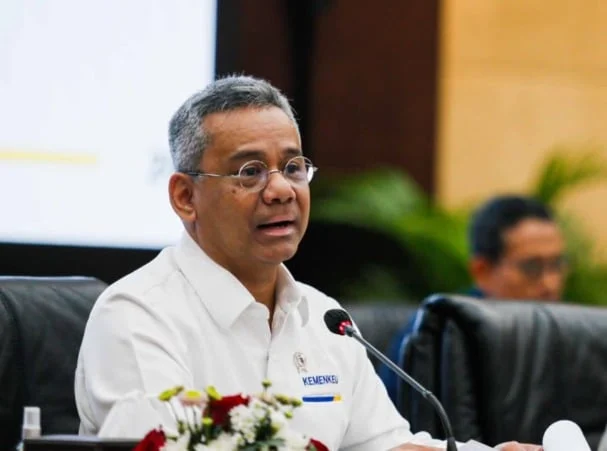
The Indonesian government has officially marked the end of a three-decade-long financial recovery journey, announcing the full settlement of all sovereign debt obligations issued to address the systemic collapse of the banking sector during the 1997-1998 Asian Financial Crisis. Deputy Finance Minister Suahasil Nazara confirmed during the APBN KiTa press conference on Friday, September 18, 2026, that the final tranche of these crisis-era instruments was retired in August 2026. This milestone signals the definitive resolution of the massive debt burden that had long defined the country’s post-Suharto macroeconomic landscape.
A Legacy of Economic Resilience
The financial crisis of 1997-1998, often referred to in Indonesia as the "Krismon," remains one of the most transformative periods in the nation’s history. Triggered by the rapid devaluation of the rupiah and a subsequent banking sector meltdown, the crisis saw the government intervene to prevent a total collapse of the financial system. To provide liquidity support to banks—many of which were on the brink of insolvency—the government issued massive amounts of recapitalization bonds and provided liquidity support known as Bantuan Likuiditas Bank Indonesia (BLBI).
According to Suahasil Nazara, the total value of the bonds issued to stabilize the economy reached approximately Rp640 trillion. While this figure was astronomical at the time, given the fiscal constraints of the late 1990s, it served as the bedrock for the subsequent restructuring of the Indonesian banking industry.
"When we look back at the history of three decades ago, the government issued a total of Rp640 trillion in bonds to handle the 1997-1998 crisis. We have now fully repaid that obligation," Suahasil stated.
Chronology of Debt Repayment
The path to debt retirement was a multi-decadal endeavor, requiring strict fiscal discipline and a long-term strategic approach to debt management. The Ministry of Finance categorized the repayment process into distinct phases based on the type of financial instrument issued.
The first major milestone in this long-term strategy was achieved in July 2020, when the government successfully settled the recapitalization bonds. These bonds were primarily issued to restore the capital adequacy ratios (CAR) of banks that had been depleted by the crisis. Following this, the government focused its efforts on the more complex and politically sensitive BLBI-related debt.
The final payment on these remaining instruments, completed in August 2026, brings an end to a legacy that has influenced every national budget for nearly 30 years. This phased approach allowed the government to balance its developmental spending priorities with the necessity of maintaining investor confidence in Indonesia’s sovereign creditworthiness.
The Mechanism of Settlement: Leveraging Central Bank Surplus
A critical component of the repayment strategy involved the coordination between the Ministry of Finance and Bank Indonesia (BI). Under the legal framework established to govern these debts, the government utilized surplus funds transferred from the central bank to the state treasury to accelerate the retirement of these obligations.
This mechanism was designed to ensure that the burden of the crisis did not rest solely on taxpayer-funded revenues, but also incorporated the operational efficiencies and gains of the central bank. Economists note that this synergy between fiscal and monetary authorities provided a stable path toward debt reduction, preventing the need for drastic austerity measures that might have otherwise hampered economic growth during the early 2000s.
Historical Context and Economic Impact
The 1997-1998 crisis did more than just create debt; it prompted a total overhaul of the Indonesian financial architecture. The establishment of the Indonesian Bank Restructuring Agency (IBRA) or Badan Penyehatan Perbankan Nasional (BPPN), and the subsequent transition to a more robust regulatory framework overseen by the Financial Services Authority (OJK), were direct responses to the shortcomings exposed during the crash.
For three decades, the servicing of these bonds represented a significant portion of the government’s interest payments, effectively diverting funds that could have been allocated to infrastructure, healthcare, or education. However, the decision to honor these commitments rather than default or renegotiate was pivotal in establishing Indonesia’s reputation as a reliable borrower in the international capital markets.
By maintaining a consistent payment schedule, Indonesia was able to regain its investment-grade status in the mid-2010s, which significantly lowered the cost of borrowing for future development projects. The completion of these payments in 2026 is viewed by market analysts as a "debt clearance" that will provide greater fiscal space for the government to manage its future economic agenda.
Analytical Perspectives: What This Means for 2026 and Beyond
The final repayment arrives at a time when the global economy is facing its own set of challenges, including fluctuating commodity prices and geopolitical shifts. With the "crisis debt" finally off the balance sheet, the government is expected to have increased flexibility in its fiscal policy.
Analysts at the Institute for Economic and Financial Reform (INDEF) have suggested that this milestone serves as a psychological and financial turning point. "The resolution of the 1998 crisis debt is a symbolic ending to the era of trauma," said one lead analyst. "It demonstrates that Indonesia has matured, transitioning from a nation reliant on bailouts to a G20 economy with a stabilized, independent fiscal structure."
However, experts also warn that while the legacy debt is gone, the focus must now shift toward managing contemporary debt levels. As of 2026, Indonesia faces new challenges related to climate financing and the need for high-tech industrial investment. The discipline required to pay off the Rp640 trillion in crisis debt serves as a historical blueprint for the current administration to maintain fiscal sustainability.
Official Statements and Future Outlook
During the press conference, Suahasil emphasized that the completion of these payments is not merely a bookkeeping exercise but a testament to the resilience of the Indonesian state. "This is a part of the history of the Indonesian financial sector. Because of the handling of the 1997-1998 crisis, our country has been able to continue with reforms and continue to carry out development up to this very moment," he remarked.
The Ministry of Finance has indicated that no new debt instruments of this nature exist on the government’s current liability ledger. The focus for the remainder of the 2026 fiscal year and beyond will be on optimizing state revenue through broader tax bases and improving the efficiency of public spending.
Conclusion: A New Chapter
The retirement of the last of the crisis-era bonds marks the end of a long, arduous process of economic rehabilitation. For a generation of policymakers who navigated the tumultuous transition from the "New Order" to the modern democratic era, the resolution of this debt represents the final closing of the books on the most difficult chapter in modern Indonesian economic history.
As Indonesia moves into the latter half of the 2020s, the government stands in a much stronger position to navigate global economic volatility. With the shadow of the 1997-1998 crisis now firmly in the rearview mirror, the focus for the state treasury turns toward the future: sustaining growth, fostering digital transformation, and ensuring that the financial stability achieved through decades of sacrifice remains intact for the next generation of Indonesians.