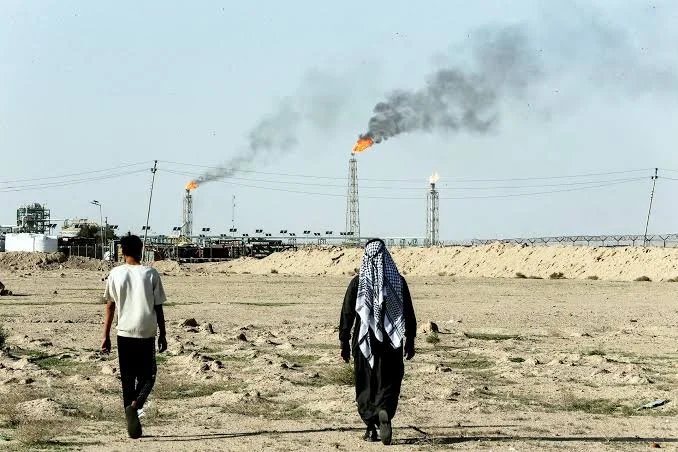
London — Global crude oil markets are currently experiencing a significant bullish trend, with prices climbing toward their fourth consecutive monthly increase as of Friday, October 30, 2026. The upward momentum is primarily driven by heightened geopolitical anxiety surrounding the ongoing conflict between the United States and Iran. Market participants are increasingly concerned that the instability, particularly regarding transit through the strategic Strait of Hormuz, could severely disrupt the global supply chain for energy.
As of 12:36 GMT, Brent crude oil futures for December delivery reached USD 117.14 per barrel, reflecting a robust increase of USD 2.26 or 2%. The more active January delivery contract also saw significant gains, rising by USD 2.30 to trade at USD 113.10 per barrel. Simultaneously, West Texas Intermediate (WTI) crude, the U.S. benchmark, climbed USD 1.94 to reach USD 103.94 per barrel, marking a 1.9% increase. These figures cap a volatile month, with Brent projected to close October with a 13% gain, while WTI is expected to finish the month approximately 15% higher.
The Strait of Hormuz: A Critical Chokepoint Under Siege
The catalyst for the latest price surge was a reported attack on a commercial tanker navigating the Strait of Hormuz. The UK Maritime Trade Operations (UKMTO) confirmed that a small vessel attached an explosive device to the tanker, marking a worrying escalation in maritime hostilities. Maritime intelligence sources have identified the weapon as a magnetic "limpet mine," the first successful deployment of such technology in the region since the onset of the U.S.-Iran conflict in February 2026.
The Strait of Hormuz represents perhaps the most critical energy chokepoint in the world. Approximately 20% of the world’s total petroleum consumption passes through this narrow waterway daily. Any sustained disruption here does not merely affect regional players; it threatens the entire global economic recovery, particularly as many nations continue to grapple with high inflation and energy-dependent industrial sectors.
Chronology of Escalation: February 2026 to October 2026
The current crisis is the culmination of months of deteriorating relations between Washington and Tehran. To understand the current market volatility, one must look at the timeline of events that have defined the year:
- February 2026: Initial hostilities erupt following the breakdown of nuclear negotiations. The U.S. imposes a series of secondary sanctions, and Iran responds by positioning naval assets near the Strait of Hormuz.
- April 2026: The first major naval skirmish occurs. Global oil prices experience an initial spike of 8% as insurance premiums for tankers operating in the Persian Gulf skyrocket.
- July 2026: A temporary diplomatic lull occurs during the G20 summit; however, the lack of a formal agreement leads to renewed skepticism from energy traders.
- September 2026: The U.S. announces a surge in military assets to the region, citing a need to "protect the freedom of navigation."
- October 30, 2026: The limpet mine attack on a tanker sends shockwaves through the futures market, cementing the trend of monthly price increases.
Market Analysis: The U.S. Midterm Factor
The timing of these market movements is inextricably linked to the upcoming U.S. midterm elections. Ole Hansen, Head of Commodity Strategy at Saxo Bank, noted that the market is bracing for political shifts. "The market is increasingly clouded by anxiety ahead of the U.S. midterm elections," Hansen stated.
Many analysts hypothesize that a potential change in legislative power could influence the administration’s foreign policy trajectory regarding Iran. There is a prevailing belief among investors that if the current administration faces pressure to take a stronger stance, further military intervention or more aggressive enforcement of oil sanctions could be on the horizon. Consequently, the "risk premium" currently baked into oil prices accounts for the high probability of further conflict in the coming weeks.
Official Responses and Diplomatic Impasse
The diplomatic landscape remains frozen. Sources within the Iranian government have signaled that there is little appetite for a rapprochement, especially while sanctions remain in place. Conversely, U.S. officials have reiterated that the "maximum pressure" campaign is intended to bring Iran back to the negotiating table.
Saul Kavonic, Head of Energy Research at MST Marquee, emphasized that the absence of a clear diplomatic roadmap is keeping prices elevated. "The persistent military activity around the Strait of Hormuz, coupled with the lack of clarity on the diplomatic front, means that the market is pricing in a high risk of further escalation," Kavonic observed.
Giovanni Staunovo, a commodities analyst at UBS, echoed this sentiment, noting that the risk-reward ratio for oil remains heavily skewed toward the upside. According to Staunovo, "The risk of further supply disruptions far outweighs the potential for a sudden, market-easing diplomatic breakthrough, which appears increasingly unlikely in the current political climate."
Broader Economic Implications and Global Risks
The surge in crude oil prices comes at a precarious time for the global economy. Earlier in the year, the World Bank warned of a potential 23% jump in global commodity prices throughout 2026, cautioning that energy inflation is a primary driver of the looming threat of a global food crisis.
High oil prices act as a multiplier for inflation. As transport costs rise, the price of goods—particularly agricultural products that require fuel-intensive machinery and logistics—inevitably follows suit. For emerging markets, which are already struggling with debt and currency devaluation, the sustained increase in energy prices represents a significant threat to fiscal stability.
Furthermore, the maritime insurance industry has begun to adjust its risk models. Many underwriters are now demanding "war risk" premiums for vessels entering the Gulf. This additional overhead cost is passed directly to the consumer, ensuring that even if crude prices were to stabilize, the final cost of refined products like gasoline and heating oil may remain elevated for the foreseeable future.
Strategic Outlook: What Happens Next?
As the global energy market moves into the final two months of 2026, the focus remains firmly on the Strait of Hormuz. The deployment of limpet mines signifies a shift from conventional naval posturing to asymmetric, "gray zone" warfare—tactics that are notoriously difficult to deter and even harder to predict.
For traders and policymakers alike, the primary variable remains the possibility of a "black swan" event. If a vessel were to be sunk or a major terminal damaged, the resulting supply shock could force Brent crude well beyond the current USD 120 per barrel threshold.
Conversely, the only factor that could provide downward pressure on prices would be a credible, verified ceasefire or a sudden de-escalation in military posturing. However, given the entrenched positions of both the U.S. and Iran, and the political imperatives surrounding the U.S. midterm elections, such an outcome appears distant.
In the immediate term, the market will likely remain in a state of high alert. Investors are advised to watch for updates from the International Maritime Organization (IMO) regarding security protocols in the region and to monitor the official rhetoric from Washington and Tehran in the days following the midterm elections. The current volatility serves as a stark reminder of the vulnerability of global energy supplies to regional conflicts and the interconnected nature of geopolitical stability and the world economy.
As October concludes, the market outlook remains distinctly cautious, with the "bullish" trend likely to persist as long as the Strait of Hormuz remains a theatre for geopolitical maneuvering rather than a conduit for stable trade.
