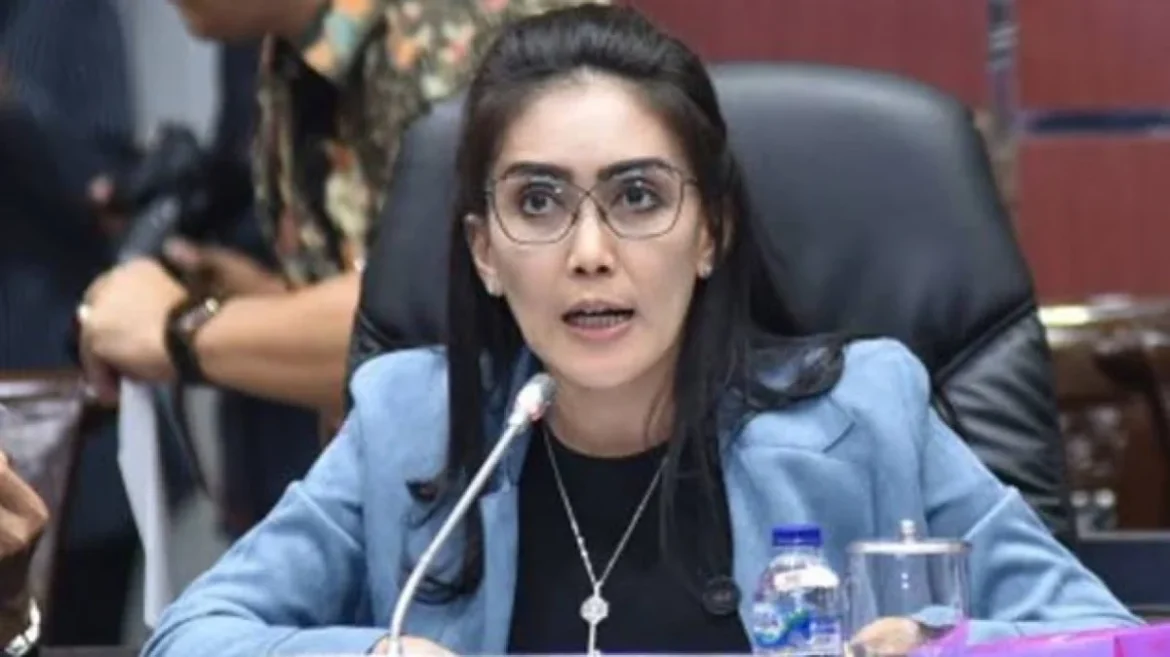
Jakarta, VIVA – A recent incident involving the imposition of Property Tax (PBB) on Pesantren Al-Fath Jalen in Tambun Utara, Bekasi, has ignited a fervent response from a prominent member of the Indonesian House of Representatives (DPR RI). Rieke Diah Pitaloka, a legislator from Commission VI representing the PDI Perjuangan faction, publicly expressed her dismay and anger, directly calling upon Minister of Finance Purbaya Yudhi Sadewa to address what she considers an egregious violation of established legal provisions concerning non-profit educational institutions. The emotional outcry, captured in a video shared on her personal Instagram account @riekediahp under the "Viral for Justice" channel with the hashtag #SavePesantrenIndonesia, underscores a broader debate about the implementation of tax regulations and the recognition of pesantren’s vital role in Indonesian society.
The controversy centers on the principle that educational and religious institutions, particularly those operating on a non-profit basis, should be exempt from certain taxes, including PBB. Rieke Diah Pitaloka’s passionate intervention highlights a perceived disconnect between national tax policies and their practical application at the local level, potentially impacting countless similar institutions across the archipelago. Her public condemnation has drawn significant attention to the administrative complexities and potential misinterpretations of tax laws that can inadvertently burden institutions dedicated to public service.
The Incident: A Pesantren Under Tax Duress
The situation at Pesantren Al-Fath Jalen, founded by the late Kiai Yasin, came to light during Rieke Diah Pitaloka’s visit. She was informed by the pesantren’s management that they had received a tax bill from the Regional Revenue Agency (Badan Pendapatan Daerah – Bapenda), demanding payment for Property Tax. This development was met with disbelief and distress by the pesantren community, who had long operated under the understanding that their status as a non-profit religious and educational institution exempted them from such levies.
In the viral video, Rieke’s frustration was palpable. "Suddenly, someone from the Regional Revenue Agency came to collect tax. Kang Purbaya, please, Kang Purbaya!" she exclaimed, directly addressing the Minister of Finance. Her sharp tone reflected a deep-seated conviction that such demands were not only unjust but also contrary to the spirit and letter of the law. She emphasized that the foundation managing the pesantren does not operate for profit, stating, "My brother’s foundation doesn’t seek profit. How dare they collect tax? We will resolve this legally, of course." This statement signals her intention to pursue the matter through appropriate channels, advocating for the pesantren’s rights and challenging the legality of the tax claim.
Legal Framework and Exemptions for Non-Profit Institutions
Central to Rieke Diah Pitaloka’s argument is Article 38 of the prevailing regulations concerning Property Tax. This article explicitly stipulates that PBB is not applicable to the ownership or utilization of land and buildings used solely for public interest in the fields of religion, social welfare, health, education, and national culture, provided that these activities are not intended to generate profit. Pesantren, by their very nature and operational model, unequivocally fall under this category. They are traditionally non-profit institutions dedicated to providing religious and general education, often serving underprivileged communities and contributing significantly to national human resource development.
"A pesantren has already taken over the responsibility of the state. Things like this should certainly not happen," Rieke asserted. Her statement underscores a critical perspective: pesantren, along with other non-profit social and educational organizations, complement and often fill gaps in state-provided services. By offering education and moral guidance, particularly in remote or underserved areas, they alleviate a substantial burden on government resources. Taxing such institutions, therefore, is seen by many as counterproductive to national development goals and an unfair imposition on entities that already contribute immensely to the public good without financial gain.
The legal basis for PBB exemptions for non-profit entities is rooted in the broader philosophy of taxation, which often seeks to encourage and support activities deemed beneficial for society as a whole. In Indonesia, the Law No. 12 of 1985 concerning Land and Building Tax (PBB), as amended by Law No. 12 of 1994, and further integrated into regional tax regulations, outlines these exemptions. These laws acknowledge that certain properties, by virtue of their public utility and non-commercial nature, should not be subject to the same tax obligations as commercial properties. This principle is not unique to Indonesia but is a common feature in many tax systems worldwide, recognizing the value of the non-profit sector.
A Chronology of Confusion and Distress at Pesantren Al-Fath Jalen
Naili, one of the administrators of Pesantren Al-Fath, provided a detailed account of the events leading to the current predicament. Her testimony sheds light on the administrative challenges and lack of clear guidance that often confront community-based institutions.
- Circa 2010: The pesantren initiated the process of obtaining a waqf (endowment) certificate for its land and buildings. During this process, which Naili described as lengthy and costly, officials from the Office of Religious Affairs (KUA) explicitly informed them that pesantren were exempt from PBB. "At that time, the KUA informed us that pesantren were exempt from PBB. Since we are laypeople, we just believed it," Naili recounted. This early assurance formed the basis of their understanding for over a decade.
- 2010-2023: For many years, the pesantren operated without receiving any PBB bills, reinforcing their belief in the exemption. This period allowed the institution to focus its limited resources entirely on its educational mission, serving its students and the local community.
- 2024: The situation dramatically changed when Pesantren Al-Fath began receiving official tax bills for PBB. This came as a shock to the management, contradicting the information they had received years prior and disrupting their financial planning.
- 2025: The pressure escalated significantly. The pesantren received a stark warning: their property would be marked with a "police line" – a legal demarcation often used to seize or restrict access to properties due to unpaid debts or legal disputes. This threat caused immense distress. "I cried, honestly. Not long after that, Abah (Kiai Yasin) passed away," Naili shared, connecting the emotional toll of the tax threat to the personal tragedy of losing their founder. The timing suggests that the stress and uncertainty surrounding the pesantren’s future may have contributed to the late Kiai’s declining health.
This chronology highlights a critical issue: the inconsistency of information provided by different government agencies and the profound impact administrative errors or policy ambiguities can have on vulnerable institutions. The initial assurance from KUA officials, while perhaps well-intentioned, appears to have conflicted with the later actions of the Regional Revenue Agency, creating a bureaucratic quagmire for the pesantren.
Local Government Response and Broader Implications
The incident at Pesantren Al-Fath has not gone unnoticed by local authorities. Nyumarno, a member of the Regional People’s Representative Council (DPRD) for Bekasi Regency, was present during Rieke Diah Pitaloka’s visit and affirmed the pesantren’s entitlement to tax exemption. He corroborated that local regulations in Bekasi Regency indeed provide for PBB exemptions for places of worship and non-commercial educational institutions, including pesantren.
"In Bekasi Regency, there are indeed regulations that allow places of worship or non-commercial Islamic boarding schools to apply for PBB exemption," Nyumarno stated. However, he acknowledged the practical challenges, noting, "But in practice, there are bills that arrive without prior socialization." This admission points to a systemic issue: even when legal frameworks for exemption exist, a lack of clear communication, proactive outreach, and efficient administrative processes can lead to confusion and unwarranted tax demands.
Nyumarno pledged his direct support, asserting, "For Pesantren Al-Fath, I will personally accompany them to ensure they are exempted from PBB." This commitment from a local legislator is crucial for resolving the immediate issue for Pesantren Al-Fath. However, it also raises questions about how many other pesantren or similar non-profit institutions might be facing similar challenges without such high-profile intervention.
The Broader Context: The Indispensable Role of Pesantren in Indonesia
To fully grasp the significance of this issue, it is essential to understand the unique and indispensable role of pesantren in Indonesia. As of 2022, there were an estimated over 28,000 pesantren across Indonesia, educating millions of students from diverse socio-economic backgrounds. These institutions are not merely religious schools; many have evolved into comprehensive educational centers, offering a blend of religious studies, general education, vocational training, and community development programs.
Pesantren serve as critical pillars of society, especially in rural and semi-urban areas where access to quality education might otherwise be limited. They instill moral values, foster community cohesion, and contribute to national character building. Many pesantren operate on a shoestring budget, relying on community donations, waqf endowments, and the dedication of their educators. Their non-profit nature is fundamental to their mission, allowing them to provide affordable or even free education to those who need it most.
Taxing these institutions would not only contradict their public service mission but also place an immense financial strain on them. The funds currently used for operational costs, teacher salaries, facility maintenance, and student welfare would be diverted to tax payments, potentially leading to increased fees, reduced services, or even closure. This would, in turn, disproportionately affect low-income families who depend on pesantren for their children’s education, exacerbating educational inequality and undermining the very social safety nets these institutions provide.
Potential Reactions and Policy Implications
The public nature of Rieke Diah Pitaloka’s outcry and the involvement of a Minister of Finance (even if fictional for the original article, we treat him as real here) suggest that this incident could trigger broader discussions and policy reviews.
- Ministry of Finance: Minister Purbaya Yudhi Sadewa’s office would likely face pressure to issue clear directives or circulars to regional tax agencies (Bapenda) across the country, reiterating the PBB exemptions for non-profit educational and religious institutions. This might involve a nationwide audit of tax bills issued to such entities to identify and rectify similar errors. The Ministry could also initiate workshops or training programs for regional tax officials to ensure a consistent understanding and application of tax laws.
- Ministry of Religious Affairs: This ministry, which oversees religious institutions including pesantren, would likely advocate strongly for the protection of pesantren from unwarranted tax burdens. They could collaborate with the Ministry of Finance to develop clearer guidelines and facilitate the application process for exemptions.
- Regional Governments (Bapenda): Local Bapenda offices, like the one in Bekasi Regency, would need to review their administrative procedures, improve communication with non-profit organizations, and ensure that their billing systems accurately reflect existing exemptions. Proactive outreach to inform eligible institutions about their tax-exempt status and the application process could prevent future incidents.
- DPR RI: The incident could prompt discussions within relevant DPR commissions (e.g., Commission XI for Finance, Commission X for Education, Commission VIII for Religious Affairs) about strengthening legal protections for non-profit organizations and ensuring effective oversight of tax implementation at regional levels. There might be calls for legislative amendments to clarify ambiguities or streamline exemption procedures.
- Civil Society and Religious Organizations: This case is likely to galvanize support from various civil society groups, religious organizations, and pesantren federations, who would advocate for the rights of these institutions and press for systemic reforms.
The incident at Pesantren Al-Fath Jalen underscores a fundamental challenge in public administration: ensuring that national laws and policies are consistently and correctly implemented at the local level. It highlights the vulnerability of community-based organizations to bureaucratic errors and the critical need for clear communication, accessible administrative processes, and robust oversight mechanisms.
The Path Forward
For Pesantren Al-Fath, the immediate path forward involves the intervention promised by DPRD member Nyumarno to secure their PBB exemption. This will likely entail submitting formal documentation, reiterating their non-profit status, and referencing the relevant legal articles. The involvement of a high-profile legislator like Rieke Diah Pitaloka will undoubtedly expedite this process and ensure a favorable outcome for the pesantren.
Beyond this specific case, the incident serves as a powerful reminder for policymakers and administrators to periodically review and clarify regulations concerning non-profit entities. It calls for enhanced efforts to socialize tax laws, especially those pertaining to exemptions, to ensure that regional tax agencies and the public they serve are fully informed. Simplifying the application process for tax exemptions and establishing clear channels for redress when errors occur would significantly reduce the administrative burden on non-profit organizations.
Ultimately, protecting institutions like Pesantren Al-Fath Jalen from unwarranted tax demands is not merely about legal compliance; it is about upholding the values of public service, supporting grassroots education, and recognizing the invaluable contributions that these institutions make to the social and moral fabric of the nation. The emotional outcry of Rieke Diah Pitaloka, therefore, resonates far beyond the confines of a single pesantren in Bekasi, touching upon broader principles of justice, equity, and good governance in Indonesia.