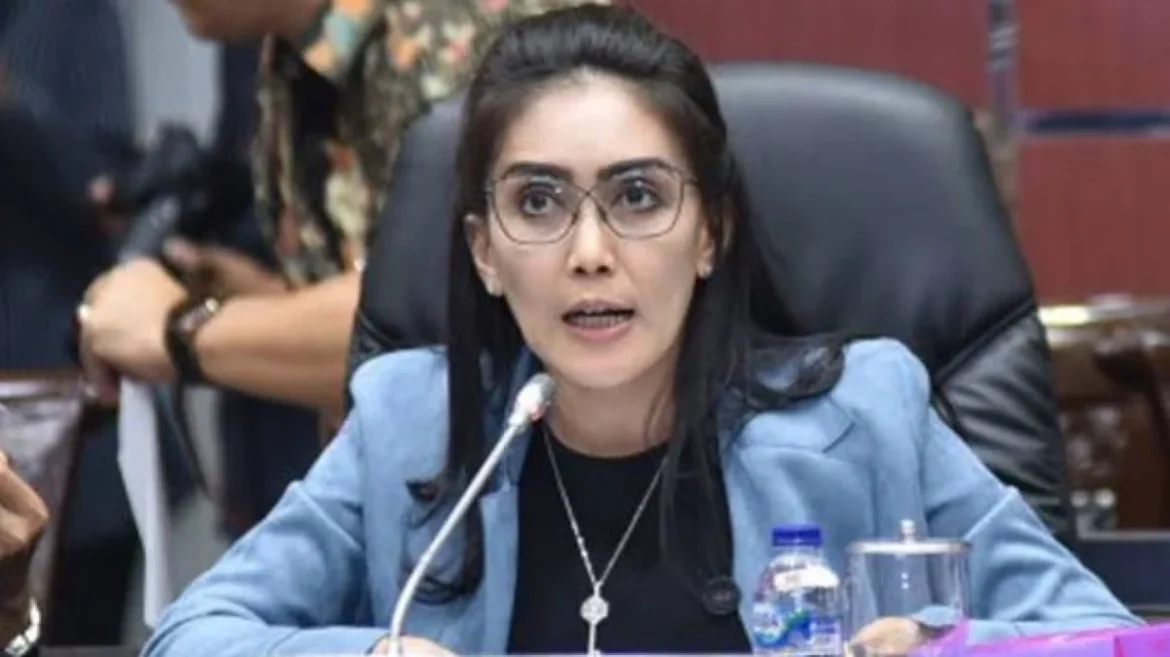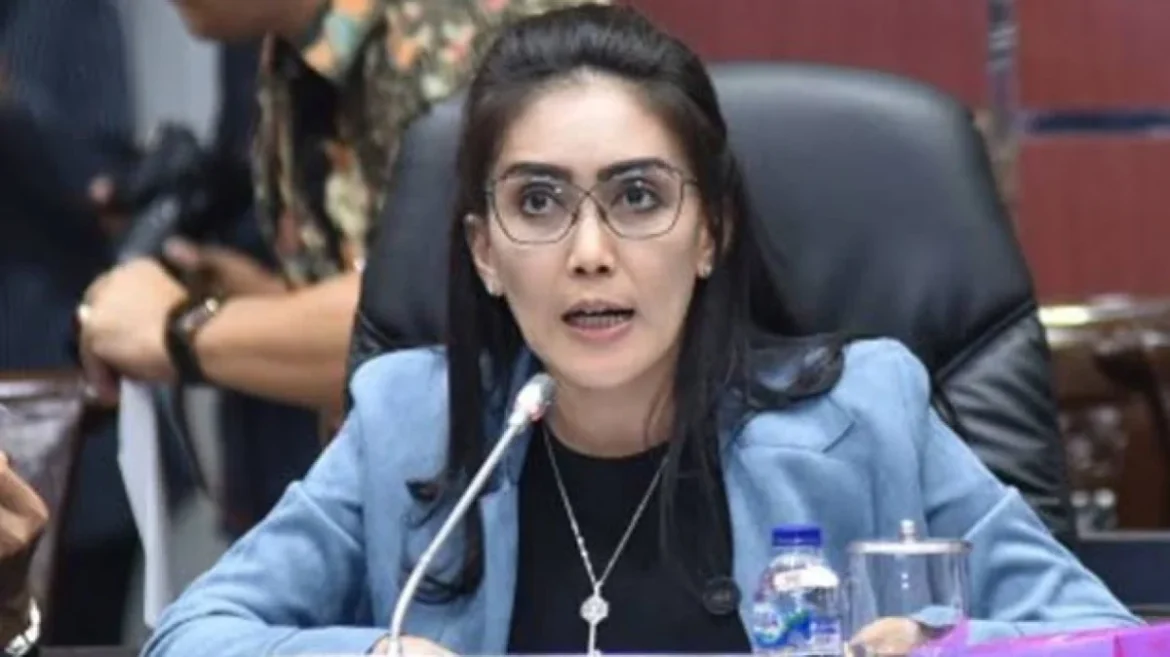
Jakarta — A wave of indignation swept through the political landscape in Indonesia following a viral social media post by Rieke Diah Pitaloka, a member of Commission VI of the House of Representatives (DPR RI) from the Indonesian Democratic Party of Struggle (PDI-P). Pitaloka openly expressed her fury after discovering that Pesantren Al-Fath Jalen, an Islamic boarding school in Tambun Utara, Bekasi Regency, founded by the late Kiai Yasin, was hit with an official demand to pay the Land and Building Tax (Pajak Bumi dan Bangunan, or PBB).
The incident, which quickly gained national traction under the Instagram hashtag #SavePesantrenIndonesia via Pitaloka’s personal channel, highlights a systemic clash between grassroots religious institutions and regional tax collection practices. Pitaloka’s emotional video appeal directly targeted newly appointed high-ranking fiscal officials, bringing to light the bureaucratic pressures placed on non-profit educational and religious sanctuaries.
Background and Context of the Controversy
Pesantren Al-Fath Jalen is a traditional Islamic educational institution that has served the community in Tambun Utara for years. Founded by the late Kiai Yasin, the boarding school operates strictly on a non-commercial basis, providing religious and general education to underprivileged youths and local community members.
In Indonesia, religious and educational institutions have historically occupied a protected status regarding state taxation. The foundational rationale is that these institutions perform public services—such as education, moral guidance, and social welfare—that technically fall under the purview of the state. By shouldering these responsibilities, religious boarding schools (pesantren) alleviate significant financial and operational burdens from the central and local governments.
However, decentralized regional autonomy has occasionally created friction between local revenue collection agencies (Badan Pendapatan Daerah, or Bapenda) and traditional institutions. Local governments face stringent targets to increase Locally Generated Revenue (Pendapatan Asli Daerah, or PAD). In their pursuit of these fiscal metrics, regional tax offices sometimes issue automated or generalized property tax assessments without thoroughly vetting the legal status or historical exemptions of specific parcels of land.
The Chronology of Events
The troubling sequence of events leading to Pitaloka’s public outcry began over a decade ago and culminated in a distressing ordeal for the school’s current administrators.
According to Naili, a key administrator at Pesantren Al-Fath, the institution’s administrative journey with land documentation began around 2010. Seeking to secure legal permanence for the property, the school management approached the local Office of Religious Affairs (KUA) to process a waqf (religious endowment) land certificate.
At the time, the process was described by administrators as lengthy and financially burdensome. However, assurances were given by local KUA officials that, as a registered Islamic boarding school, the property was legally exempt from the Land and Building Tax (PBB). Operating with limited legal literacy and placing trust in the verbal guidance of state religious representatives, the management did not pursue further independent tax registrations, assuming the property was entirely safeguarded under the law.
For years, this understanding held true, and the school continued its educational mission undisturbed. The situation shifted dramatically, however, in 2024, when the institution began receiving unexpected formal tax billing notices from the regional revenue authorities.
The pressure escalated sharply into 2025. Administrators were reportedly hit with formal warnings threatening extreme enforcement measures, including the installation of police lines on the school premises if the outstanding tax liabilities were not settled immediately. The psychological toll on the aging founder and the management team was severe. Naili recounted to Pitaloka that the stress of the impending enforcement actions deeply affected the late Kiai Yasin during his final days, coinciding with a period of declining health that ultimately led to his passing.
Legislative Arguments and Legal Framework
During her on-site visit to Pesantren Al-Fath, Rieke Diah Pitaloka did not mince words. Standing on the school grounds, she addressed the situation not merely as an administrative oversight, but as an affront to justice. In her viral video message, she directly called upon prominent fiscal leadership, shouting, “Suddenly people come from the Regional Revenue Agency collecting taxes. Kang Purbaya, please, Kang Purbaya.”
Pitaloka underscored that the foundation running the institution operates entirely on a philanthropic, non-profit basis. She forcefully argued that targeting such facilities contradicts the established legal framework governing property taxation in Indonesia.
To substantiate her claims, Pitaloka cited specific legal protections, referencing Article 38 of the prevailing regulations concerning the Land and Building Tax. The statute explicitly dictates that PBB obligations do not apply to the ownership, control, or utilization of land and buildings used exclusively for public interest purposes encompassing religion, social welfare, health, national education, and culture, provided that these activities are not commercial or profit-driven.
“The pesantren has essentially taken over the responsibilities of the state. Things like this certainly should not happen,” Pitaloka declared, emphasizing the symbiotic relationship that ought to exist between public governance and religious education infrastructure.
Local Government and Political Reactions
The fallout from the viral video prompted immediate responses from local legislative representatives. Nyumarno, a member of the Bekasi Regency Regional House of Representatives (DPRD), rushed to the scene to assess the situation alongside Pitaloka and provide clarity on local regulatory mechanics.
Nyumarno corroborated the school administrators’ position, affirming that regional bylaws in Bekasi Regency explicitly protect places of worship and non-commercial educational facilities from property tax liabilities.
“In Bekasi Regency, there are indeed established regulations stating that places of worship or non-commercial Islamic boarding schools can apply for a full exemption from paying PBB,” Nyumarno stated during the dialogue.
However, Nyumarno acknowledged a persistent structural disconnect in bureaucratic execution. He noted that in practical implementation, administrative notices and tax bills are frequently generated and dispatched automatically without adequate field verification or prior social outreach. This systemic flaw often results in historical or exempt institutions suddenly receiving intimidating collection letters.
Addressing the immediate crisis at Pesantren Al-Fath, Nyumarno offered a firm commitment to intervene directly on behalf of the institution. He assured the school’s leadership that he would personally accompany them through the bureaucratic channels required to nullify the outstanding tax bills and secure formal, permanent tax-exempt status.
Broader Implications and Systemic Issues
The incident at Pesantren Al-Fath Jalen serves as a microcosm of wider administrative challenges facing thousands of traditional educational institutions across the Indonesian archipelago. While national laws and regional bylaws provide clear exemptions for religious and educational entities, the decentralization of tax administration has created vulnerabilities.
Regional governments are under continuous pressure to maximize local revenue streams to fund regional development. Consequently, local tax offices often utilize digital mapping and broad property assessment databases that register all land parcels within a given zone without cross-referencing ministerial registries of religious endowments or educational foundations.
For many traditional boarding schools, which are often established on family-donated land and managed by generations of clerics with limited administrative sophistication, navigating modern bureaucratic tax systems presents a formidable barrier. When faced with official documents bearing legal threats, such as potential asset seizures or police lines, administrators—frequently unfamiliar with dispute resolution mechanisms—experience profound distress.
Furthermore, the involvement of high-profile national legislators like Rieke Diah Pitaloka and local parliamentarians highlights how social media has transformed grievance redressal in Indonesia. Grassroots complaints that might have previously lingered in bureaucratic limbo for months can now be amplified instantly, compelling swift political intervention and institutional accountability.
Conclusion and Future Outlook
The public outcry surrounding Pesantren Al-Fath Jalen has placed local tax authorities under intense scrutiny, forcing a re-evaluation of how regional revenue collection agencies interact with protected non-profit entities. While the immediate outcome for Pesantren Al-Fath appears promising—backed by the direct intervention of regional legislators committed to rectifying the billing error—the broader systemic issue remains unresolved.
Experts and policymakers suggest that preventing recurrence requires tighter institutional coordination between the Ministry of Religious Affairs, the National Land Agency (BPN), and regional revenue boards. Establishing an integrated, automated database of tax-exempt religious and educational assets could preemptively eliminate erroneous billings, sparing vulnerable institutions from administrative intimidation and ensuring that the foundational spaces of community education and spiritual guidance are rigorously safeguarded by the state they serve.