Monday, July 20, 2026 – 17:00 WIB
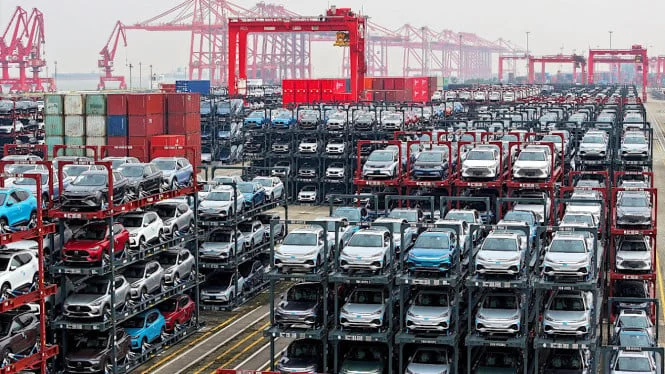
The Chinese automotive industry, a powerhouse of global manufacturing and a frontrunner in electric vehicle (EV) adoption, is currently navigating a complex economic landscape marked by significant financial pressures. Despite robust sales of electric vehicles and aggressive international expansion strategies, a number of major Chinese automakers are projecting considerable declines in profitability for the first half of 2026, with several anticipating net losses. This financial strain signals a potential turning point for an industry that has experienced meteoric growth in recent years.
A review of financial projections released by six prominent Chinese car manufacturers reveals a stark reality. Four companies are forecasting net losses for the first half of the year, while the remaining two, though still profitable, expect their earnings to be slashed by more than half compared to the same period in 2025. This widespread downturn underscores the multifaceted challenges confronting the sector, ranging from escalating production costs to intensified market competition and currency fluctuations.
Key Players Face Significant Financial Setbacks
Among the most severely impacted is the GAC Group (Guangzhou Automobile Group Co., Ltd.), which anticipates a net loss between 4.06 billion and 4.57 billion yuan for the first six months of 2026. The company attributes this projected deficit to a confluence of factors, including a significant rise in raw material prices, increased expenditure on sales and marketing initiatives, a decline in revenue from its joint ventures with foreign automakers, and volatile foreign exchange rates. These pressures have collectively eroded GAC’s profit margins, despite its efforts to maintain market share.
Seres Group, another prominent automaker, is also predicted to swing into a net loss, estimating a deficit of approximately 1.5 billion to 1.8 billion yuan. The company points to shifts in raw material costs and disruptions within its supply chain as the primary drivers of this financial downturn. The intricate global supply networks upon which modern automotive manufacturing relies have proven susceptible to various economic and geopolitical shocks, impacting Seres’s ability to manage its cost base effectively.
BAIC BluePark New Energy Technology Co., Ltd., a subsidiary of Beijing Automotive Group, is projecting a net loss ranging from 1.77 billion to 1.97 billion yuan. In addition to the rising costs from suppliers, the company is burdened by substantial investments in research and development (R&D) for next-generation automotive technologies. Furthermore, BAIC BluePark has yet to achieve optimal production scale, a factor that often inflates per-unit manufacturing costs and hinders profitability in the early stages of new model introductions.
JAC Motors (Anhui Jianghuai Automobile Group Co., Ltd.) is also forecasting a net loss, estimated at around 740 million yuan. The company cites a decline in overall sales volume, a weakening performance from its joint venture operations, and the impact of currency exchange rate fluctuations as key contributors to its projected financial results. These factors highlight the interconnectedness of sales, partnerships, and macroeconomic conditions in shaping a company’s financial health.
Resilience Amidst Challenges: Changan and Great Wall Motor
In contrast to the widespread losses, Changan Automobile and Great Wall Motor are still expected to report profits. However, even these more resilient players are experiencing a significant dip in earnings. Changan Automobile, for instance, anticipates a net profit decrease of approximately 57.7% to 67.7% compared to the first half of 2025. This reduction is attributed to the same escalating raw material costs and currency volatility affecting other manufacturers, coupled with increased investment aimed at bolstering their overseas market presence.
Great Wall Motor, known for its SUV and pickup truck segments, has not yet released specific profit projections for the first half of 2026. However, industry analysts anticipate that the company will also face margin compression due to the same cost pressures and competitive landscape impacting its peers.
The Dual Squeeze: Rising Costs and Fierce Competition
The challenges confronting the Chinese automotive industry are not solely confined to the cost of production. A fiercely competitive domestic market is exerting additional pressure, forcing many manufacturers to offer significant discounts to maintain or gain market share. This aggressive pricing strategy, while beneficial to consumers in the short term, places considerable strain on automakers’ profitability, especially when they are simultaneously investing heavily in R&D for new technologies and launching innovative models to stay ahead of the curve.
The first half of 2026 has been particularly challenging due to a sharp increase in the prices of various critical components, including automotive memory chips. This surge in input costs makes it increasingly difficult for manufacturers to protect their profit margins, even when sales volumes remain strong in certain segments.
Background and Context: A Sector in Transition
The Chinese automotive sector has experienced an unprecedented period of growth over the past two decades, transforming from a nascent industry to a global leader. The government’s strong support for electric vehicles, coupled with a rapidly growing middle class and robust domestic demand, fueled this expansion. Chinese brands have not only dominated their home market but have also begun to challenge established international players in global markets, particularly in the EV segment.
However, this rapid ascent has been accompanied by inherent vulnerabilities. The industry’s reliance on global supply chains, its significant investment in new technologies, and the intense competition have created a complex ecosystem susceptible to economic fluctuations. The current financial headwinds can be viewed as a maturation phase for the industry, where companies are being tested on their operational efficiency, cost management, and strategic adaptability.
The push for electrification, while a key driver of growth, also necessitates massive capital expenditure. Companies are investing heavily in battery technology, autonomous driving systems, and software development, all of which add to their financial obligations. The current economic climate, characterized by rising inflation and potential global economic slowdowns, exacerbates these investment burdens.
Chronology of Pressures
- Late 2025 – Early 2026: Initial signs of increasing raw material costs, particularly for key metals and electronic components, begin to emerge.
- First Quarter 2026: Supply chain disruptions, influenced by geopolitical events and logistical challenges, lead to increased lead times and higher component prices.
- April-June 2026: Major Chinese automakers begin to release preliminary financial data and forecasts for the first half of the year, indicating significant profit erosion.
- Mid-July 2026: Public announcements and projections from GAC Group, Seres, BAIC BluePark, and JAC Motors reveal anticipated net losses, highlighting the severity of the financial strain. Changan Automobile also forecasts a substantial decline in profits.
Supporting Data and Market Trends
While specific sales figures for the first half of 2026 are still being compiled, industry analysts have noted a sustained demand for electric vehicles, which have become a significant segment of the Chinese auto market. However, the overall automotive market is facing pressure from a slowing economy and cautious consumer spending.
- EV Penetration: China continues to lead the world in EV adoption, with electric and plug-in hybrid vehicles accounting for a substantial and growing share of new car sales. This trend, while positive for long-term growth, requires continuous investment in R&D and manufacturing capacity.
- Component Costs: The price of lithium, a key component in EV batteries, has seen volatility, impacting production costs. Similarly, semiconductor shortages and price hikes have affected the entire automotive industry globally, including China.
- Global Expansion: Many Chinese automakers are actively expanding into international markets, particularly in Europe and Southeast Asia. While this offers growth opportunities, it also requires significant investment in marketing, distribution, and localization, adding to financial pressures.
Broader Impact and Implications
The financial struggles of these prominent Chinese automakers have several significant implications for the global automotive landscape:
- Intensified Competition: Companies facing profit pressure may become more aggressive in their pricing strategies, potentially leading to price wars that could benefit consumers but squeeze margins further for all players.
- Consolidation: A period of financial distress could lead to mergers and acquisitions within the industry as stronger players absorb weaker ones, potentially reshaping the competitive landscape.
- Shift in Investment Priorities: Companies might re-evaluate their R&D spending and international expansion plans, potentially slowing down the pace of innovation or global market entry.
- Impact on Global Supply Chains: The financial health of major Chinese manufacturers is critical for their suppliers, both domestic and international. A significant downturn could have ripple effects across the global automotive supply chain.
- Geopolitical Considerations: As Chinese automakers expand globally, their financial performance and strategic decisions will be closely watched by governments and regulators in key markets.
The current financial challenges represent a critical juncture for the Chinese automotive industry. While its commitment to electrification and innovation remains strong, the sector must now demonstrate its ability to navigate economic headwinds, manage costs effectively, and adapt to a rapidly evolving global market. The resilience and strategic decisions of these automakers in the coming months will be crucial in determining the future trajectory of China’s automotive powerhouse.