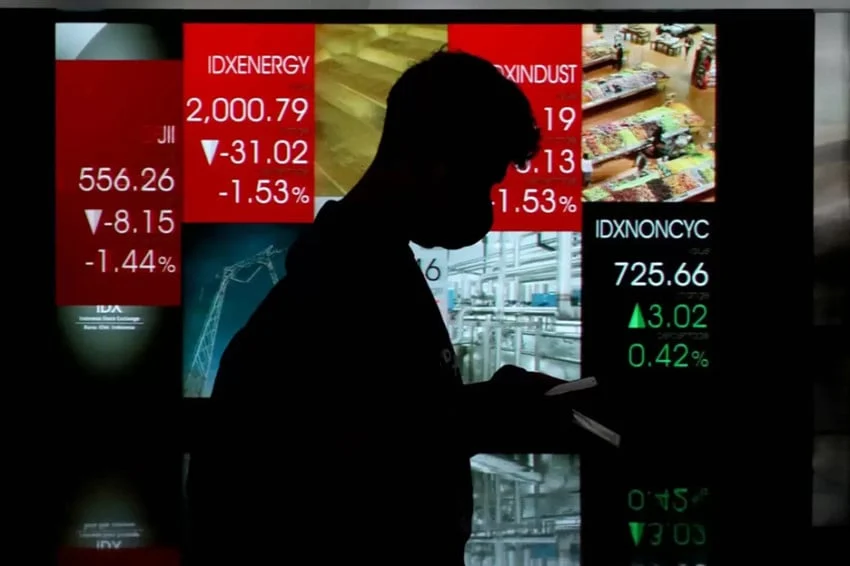
The Jakarta Composite Index (Indeks Harga Saham Gabungan – IHSG) closed deep in negative territory at the end of the trading session on Friday, September 25, 2026, pressured by widespread selling across almost all major sectors. The benchmark index dropped significantly by 56.72 points, or 0.90 percent, to settle at the 6,241 level. The market downturn reflected prevailing investor caution and risk-off sentiment dominating the domestic financial landscape, as market participants weighed various domestic economic indicators alongside evolving global macroeconomic conditions.
Throughout the trading day, market breadth heavily favored the negative side. Official stock exchange data indicated that only 122 equities managed to record gains, while a staggering 587 stocks suffered declines. Meanwhile, 254 stocks remained unchanged, reflecting a lack of strong buying catalysts to counter the downward pressure. Total transaction value reached IDR 9.3 trillion, with a total volume of 26.2 billion shares changing hands across the board.
The negative sentiment was not limited to the headline index; all major sub-indexes and sectoral groupings experienced uniform corrections. Major market barometers such as the LQ45 index, which tracks the 45 most liquid stocks on the exchange, fell by 0.34 percent to 621. Similarly, the Jakarta Islamic Index (JII) decreased by 0.92 percent to 372, the IDX30 index declined by 0.33 percent to 344, and the MNC36 index slipped by 0.44 percent to finish at 269. The comprehensive sectoral breakdown showed a completely unified red board, with energy, non-cyclical consumer goods, financials, properties, basic materials, transportation, industrials, cyclical consumer goods, infrastructure, healthcare, and technology sectors all closing in negative territory.
Chronology of Friday’s Trading Session
The trading session on Friday, September 25, 2026, began with a brief moment of optimism. The IHSG had initially opened in the green, rising 0.27 percent to touch the 6,315 level during the early morning bell. This initial positive momentum raised hopes among retail and institutional investors that the market might recover from the previous day’s lackluster performance, where the index had already shown signs of structural weakness and closed pressed down at 6,298 amid a heavy fall of 487 stocks.
However, the early gains proved to be short-lived. As the trading day progressed into the afternoon session, persistent selling pressure materialized across bellwether banking and energy counters. Foreign capital outflows and profit-taking activities accelerated past midday. By the final closing bell, the index had breached multiple psychological support levels, eventually settling at 6,241. This sharp reversal underscored the fragile nature of market sentiment during the session, leaving traders with little room to maneuver as selling momentum intensified toward the end of the day.
Top Gainers and Losers Amid the Market Downturn
Despite the broad-based market correction, several individual stocks managed to defy the downward trend, delivering substantial gains for selective investors who engaged in high-risk trading strategies.
Topping the list of top gainers was PT Martina Berto Tbk (MBTO), which surged by an impressive 34.64 percent to close at IDR 206 per share. Following closely behind was the Reksa Dana Syariah Indeks Simas ETF JII, which recorded a 32.81 percent increase to reach IDR 85. Rounding out the top three gainers was PT Hotel Sahid Jaya International Tbk (SHID), which climbed 24.83 percent to finish the day at IDR 905 per share. These localized rallies were largely driven by speculative interest rather than systemic sector-wide fundamentals.
Conversely, heavy losses were recorded by several equities that featured prominently on the top losers list. PT Citatah Tbk (CTTH) led the downward spiral, plunging 14.96 percent to IDR 108. It was closely matched by PT Wahana Inti Makmur Tbk (NASI), which also dropped 14.96 percent to close at IDR 199. Another notable loser was PT Olympus Strategic Indonesia Tbk (NATO), which fell 14.92 percent to settle at IDR 1,055 per share. The steep declines in these counters reflected aggressive profit-taking and a lack of buying support following recent speculative runs.
Broader Market Context and Economic Background
The sharp contraction in the IHSG on Friday comes against a backdrop of heightened global financial market volatility and localized economic recalibrations. Emerging market economies, including Indonesia, continue to navigate a complex matrix of external pressures, ranging from shifting central bank monetary policies in advanced economies to fluctuating commodity prices on the international market.
Domestic investors have been closely monitoring corporate earnings reports, inflation trajectories, and Bank Indonesia’s monetary stance. The simultaneous decline across all sectoral indices indicates that the market correction was not isolated to a single industry or asset class, but rather reflected a holistic reassessment of equity valuations by institutional portfolio managers. Analysts note that when financial, energy, and consumer goods sectors simultaneously retreat, it typically points to a macro-driven capital reallocation rather than sector-specific adverse news.
Market Implications and Future Outlook
The closure of the IHSG at the 6,241 level has raised concerns among technical analysts regarding short-term market trajectory. Sustained closes below key psychological thresholds often prompt automated stop-loss mechanisms and margin calls, which can exacerbate downward pressure in subsequent trading sessions.
Market observers suggest that investors should maintain a defensive posture in the near term, focusing on companies with robust balance sheets, strong fundamental earnings, and stable dividend yields. Furthermore, market participants are advised to closely monitor upcoming macroeconomic releases, including monthly trade balance figures, foreign exchange reserve data, and domestic inflation metrics, which will serve as critical determinants for the market’s direction in the coming weeks. While volatility is expected to persist, strategic investors often view such sharp market corrections as an opportunity to accumulate fundamentally sound assets at more attractive valuations over a longer-term investment horizon.