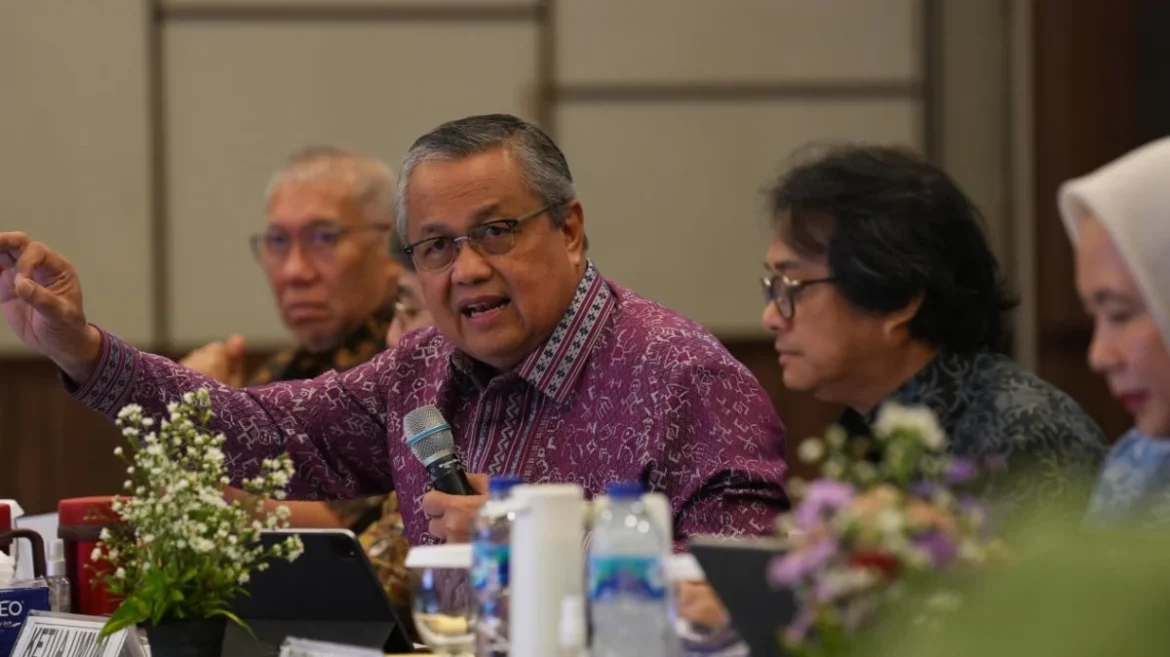
Jakarta, VIVA – Bank Indonesia (BI) Governor Perry Warjiyo has issued a robust call for enhanced fiscal and monetary policy synergy, emphasizing its critical role in navigating the escalating uncertainties pervading the global economy and financial markets. The pronouncement came during a teleconference press conference following BI’s Board of Governors Meeting (RDG) on Wednesday, July 22, 2026, where the central bank assessed the latest economic developments and outlined its forward-looking strategies. The governor’s remarks underscore a growing concern over a complex web of geopolitical tensions, commodity market volatility, and a tightening global monetary landscape that collectively threaten stability and growth prospects worldwide.
The Re-escalation of Global Tensions: A Catalyst for Uncertainty
The primary driver behind the renewed surge in global uncertainty, as highlighted by Governor Warjiyo, is the re-escalation of hostilities between the United States and Iran in early July 2026. This geopolitical flashpoint has had immediate and tangible consequences, particularly impacting the vital Strait of Hormuz. The Strait, a narrow waterway connecting the Persian Gulf to the open ocean, is a crucial chokepoint for global oil shipments, with an estimated 20-30 percent of the world’s seaborne crude oil passing through it daily. Any disruption in this strategic maritime artery sends immediate shockwaves through international energy markets and global supply chains.
The latest iteration of this long-standing geopolitical friction has led to renewed impediments to maritime traffic in the Strait of Hormuz. This disruption has, in turn, severely hampered oil production and inter-country trade supply chains, causing a sharp reversal in the trajectory of global oil and various other commodity prices, which had previously shown signs of stabilization. The immediate upswing in these prices directly contributes to inflationary pressures worldwide, complicating the monetary policy decisions of central banks globally. The history of US-Iran relations is marked by periods of intense tension and sanctions, often spilling over into regional proxy conflicts and threats to maritime security, making the Strait of Hormuz a recurring flashpoint with significant global economic ramifications. The July 2026 re-escalation serves as a stark reminder of how geopolitical events can swiftly derail economic forecasts and necessitate urgent policy responses.
Global Economic Headwinds and Forecasts
Against this backdrop of heightened geopolitical risk, the global economic outlook for 2026 remains challenging. Governor Warjiyo reiterated that world economic growth is projected to remain subdued at approximately 3 percent. This figure, while positive, represents a deceleration from previous years and reflects the cumulative impact of ongoing structural challenges, lingering post-pandemic recovery imbalances, and the fresh blow from geopolitical events. Simultaneously, global inflation is anticipated to escalate further, reaching around 4.5 percent. This upward revision in inflation forecasts is largely attributed to the commodity price surges stemming from the Strait of Hormuz disruptions, alongside persistent supply-side bottlenecks and robust demand in certain sectors.
In response to these mounting inflationary pressures, global monetary policies are poised to become even tighter. The US Federal Reserve, for instance, is now expected to accelerate its policy normalization efforts, with a rate hike in the Fed Funds Rate (FFR) projected to occur earlier, specifically in the fourth quarter of 2026. This anticipated move by the world’s most influential central bank signals a more aggressive stance to tame inflation, even at the risk of potentially dampening economic activity. The market has already begun pricing in this hawkish shift, evident in the significant rise in US Treasury yields. On July 20, 2026, the yield on the benchmark 10-year US Treasury bond climbed to 4.56 percent, while the 2-year yield reached 4.18 percent. These yields, considered benchmarks for global borrowing costs, are expected to increase further, driven not only by tighter monetary policy expectations but also by the widening fiscal deficit in the United States, which necessitates increased government borrowing.
The ripple effects of these developments are profound for global financial markets. The shift towards higher yields in the US and the perceived safety of American assets has triggered a notable flight of capital from emerging markets. Investors, seeking higher returns and greater security, are reallocating funds towards US financial markets and other safe-haven assets. This capital outflow has, in turn, fueled a strengthening of the US dollar against both major developed market currencies (reflected in the DXY index) and emerging market currencies (as seen in the ADXY index). A stronger dollar makes imports more expensive for countries with weaker currencies, exacerbating imported inflation and complicating external debt management.
Indonesia’s Domestic Resilience Amidst External Shocks
Despite the turbulent global landscape, Indonesia’s economy has demonstrated commendable resilience, with growth remaining well-maintained, primarily underpinned by robust domestic demand. The central bank’s assessment for the second quarter of 2026 revealed several key strengths in the domestic economy.
Government consumption, a significant component of aggregate demand, recorded high growth. This was buoyed by the continued realization of various national priority programs, reflecting strategic fiscal interventions aimed at stimulating economic activity. A key factor contributing to this surge was the acceleration of government spending, notably the disbursement of the 13th-month salary for civil servants (ASN) and the distribution of social assistance to eligible beneficiary families (KPM). These measures provided a direct injection of liquidity into the economy, boosting purchasing power and consumption.
Household consumption, the largest component of Indonesia’s GDP, also remained strong. This was supported by a suite of government stimuli designed to alleviate cost-of-living pressures and encourage spending. These programs included targeted food assistance, transportation tariff discounts, and national vocational training and meal programs, which collectively helped maintain consumer confidence and spending capacity.
Investment, a crucial driver of long-term economic growth, continued to expand, predominantly supported by building investment related to the realization of National Priority Work Programs (PKPN). Large-scale infrastructure projects and public works initiatives under these programs generated significant economic activity and employment. However, Governor Warjiyo underscored the persistent need to further boost private sector investment, recognizing its pivotal role in diversifying growth sources and enhancing long-term competitiveness.
From an external perspective, while the global growth outlook remains sluggish, Indonesia’s export performance needs continuous strengthening. This is crucial to capitalize on the prevailing high global commodity prices, which, despite the global slowdown, still offer opportunities for export revenue generation. Indonesia, as a major exporter of commodities such as palm oil, coal, and nickel, can leverage these elevated prices to maintain a healthy trade balance, though the overall volume might be constrained by weaker global demand.
Sectorally, several key economic fields continued to exhibit strong growth, aligning with the implementation of government programs. These included the manufacturing industry, construction, transportation, and warehousing sectors. The manufacturing sector benefited from domestic demand and export opportunities, while construction was propelled by infrastructure development. The transportation and warehousing sectors saw increased activity corresponding to enhanced logistics and supply chain efficiency, reflecting ongoing investments in connectivity and trade facilitation.
The Imperative of Policy Synergy: Fiscal and Monetary Coordination
The call for strengthened fiscal and monetary policy synergy by Governor Perry Warjiyo is not merely a recommendation but an imperative in the current volatile environment. This coordination is deemed essential for several reasons: bolstering external resilience, safeguarding domestic stability, and fostering sustainable economic growth.
Fiscal policy, managed by the Ministry of Finance, involves government spending, taxation, and debt management. In Indonesia, the government has historically used fiscal tools to stimulate demand, provide social safety nets, and invest in infrastructure. Monetary policy, conducted by Bank Indonesia, involves managing interest rates, liquidity, and the exchange rate to control inflation and maintain financial stability. In an increasingly interconnected and uncertain world, the independent actions of these two policy arms, if not harmonized, can sometimes work at cross-purposes, diluting their overall effectiveness.
For instance, if BI tightens monetary policy to curb inflation and manage capital outflows, but fiscal policy remains overly expansive, it could create a push-pull dynamic. Conversely, if fiscal policy is constrained while monetary policy is accommodative, it might not generate sufficient stimulus. The synergy envisioned by Governor Warjiyo implies a coordinated approach where fiscal measures, such as targeted subsidies, infrastructure spending, or tax incentives, complement BI’s monetary actions. For example, if BI raises interest rates to stabilize the Rupiah and combat imported inflation, the government could simultaneously implement targeted social assistance programs to mitigate the impact of higher borrowing costs on vulnerable households and businesses. Similarly, fiscal discipline in managing the budget deficit can reduce pressure on government bond yields, indirectly supporting BI’s efforts to maintain market stability.
Indonesia has a history of joint fiscal and monetary responses, particularly during times of crisis. The "burden-sharing" mechanism, where BI directly participates in financing the state budget deficit in extraordinary circumstances, exemplifies such coordination. While such direct financing is typically reserved for emergencies, regular consultations and aligned policy objectives between BI and the Ministry of Finance are standard practice. The current global environment, characterized by simultaneous shocks to supply, demand, and financial markets, necessitates an even higher degree of integration in policymaking. This means clear communication, shared economic assessments, and mutually reinforcing strategies to ensure that the combined force of government and central bank actions is maximally effective in achieving national economic objectives.
Potential Implications for Indonesia
The heightened global uncertainties and the call for stronger policy synergy carry significant implications for Indonesia’s economic trajectory:
- Monetary Policy Adjustments: Bank Indonesia may be compelled to maintain a hawkish stance or even tighten monetary policy further to counter imported inflation stemming from rising commodity prices and to stabilize the Rupiah amidst capital outflows. This could involve further interest rate hikes or more aggressive intervention in the foreign exchange market, potentially impacting domestic borrowing costs and economic activity.
- Fiscal Policy Challenges: The government’s fiscal space might face pressure. Rising global oil prices could inflate energy subsidy bills, while higher interest rates on US Treasuries could increase the cost of borrowing for the Indonesian government on international markets. Fiscal prudence and efficient resource allocation will be paramount to maintaining the budget deficit within sustainable limits (e.g., below 3% of GDP, as mandated by law) while continuing to support priority programs and social safety nets.
- Trade and Current Account: While high commodity prices could support export values, a global economic slowdown might reduce overall export volumes. Simultaneously, a depreciating Rupiah could make imports more expensive, potentially widening the trade deficit in certain non-commodity sectors and putting pressure on the current account balance. Sustained efforts to diversify export markets and products will be crucial.
- Inflationary Pressures: Indonesia faces the risk of increased imported inflation, particularly for energy and food items. BI’s commitment to its inflation target (typically 2-4%) will be tested, requiring careful management of aggregate demand and supply-side policies in coordination with the government.
- Investment Climate: Global uncertainty and capital flight to safe havens could dampen foreign direct investment (FDI) inflows into Indonesia. Domestically, higher interest rates could also slow private sector investment. Therefore, government efforts to improve the ease of doing business, provide investment incentives, and ensure regulatory certainty become even more critical to attract and retain capital.
- Exchange Rate Volatility: The strengthening US dollar against emerging market currencies, including the Rupiah, is likely to persist. This volatility complicates import planning for businesses, increases the burden of foreign currency-denominated debt, and requires active intervention from BI to maintain stability without depleting foreign exchange reserves excessively.
Reactions and Expert Perspectives
Economists and financial analysts largely concur with Governor Warjiyo’s assessment, emphasizing that a fragmented approach by policymakers could exacerbate vulnerabilities. Many observers expect the Ministry of Finance to reaffirm its commitment to fiscal sustainability and targeted spending, aligning with BI’s stability objectives. Experts from institutions like the Institute for Development of Economics and Finance (INDEF) or the Centre for Strategic and International Studies (CSIS) would likely highlight the importance of timely and transparent communication between BI and the Ministry of Finance to manage market expectations effectively. They might also stress the need for structural reforms, such as improving human capital and infrastructure, to enhance Indonesia’s long-term resilience against external shocks. While specific statements from other parties were not immediately available, the general consensus would lean towards an urgent and unified response to mitigate the potentially severe impacts of a deteriorating global economic environment.
Looking Ahead: Navigating a Complex Global Landscape
The global economic landscape in mid-2026 presents a formidable array of challenges, from geopolitical conflicts and commodity price shocks to persistent inflationary pressures and tighter monetary conditions. For Indonesia, navigating this complexity requires not only vigilance and adaptability but, crucially, a highly coordinated and strategic approach from its economic policymakers. Governor Perry Warjiyo’s call for strengthened fiscal and monetary synergy serves as a timely reminder that in an era of cascading global uncertainties, a united front is the most effective defense. The ability of Bank Indonesia and the government to work in concert, leveraging their respective policy tools effectively, will be pivotal in ensuring Indonesia’s continued economic stability, growth, and resilience against the volatile tides of the global economy.