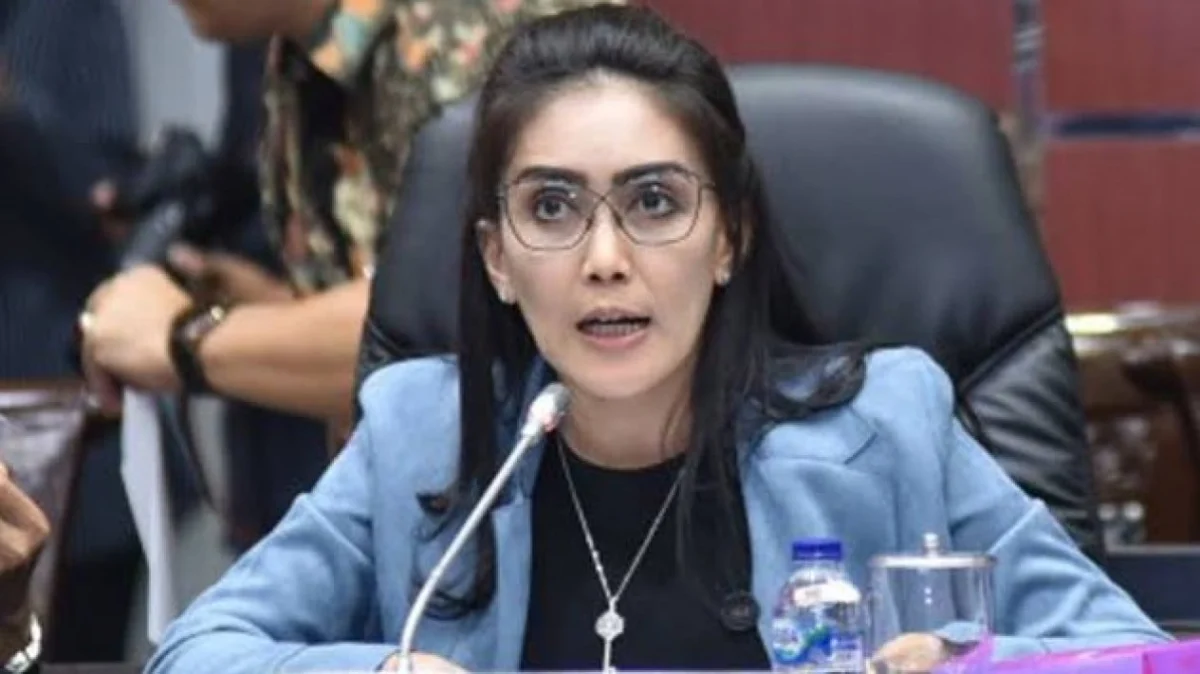
Jakarta — A wave of indignation has rippled across Indonesia following a public outcry led by Rieke Diah Pitaloka, a member of Commission VI of the House of Representatives (DPR RI) representing the Indonesian Democratic Party of Struggle (PDI-P). Pitaloka expressed profound anger and disbelief after discovering that Pesantren Al-Fath Jalen, an Islamic boarding school founded by the late Kiai Yasin in Tambun Utara, Bekasi Regency, was slapped with continuous property tax bills under the Pajak Bumi dan Bangunan (PBB) framework.
The controversy erupted after Pitaloka uploaded a video to her personal Instagram account under the handle @riekediahp, utilizing the digital campaign channel Viral for Justice alongside the hashtag #SavePesantrenIndonesia. In the widely circulated footage, the lawmaker can be seen visibly emotional, raising her voice to directly address Finance Minister Purbaya Yudhi Sadewa.
The incident has since ignited a broader national debate regarding the taxation of non-profit religious and educational institutions in Indonesia, drawing scrutiny toward local tax collection practices, regulatory oversights, and the fundamental social responsibilities of the state toward educational entities that operate for the public good.
Chronology of Events: From Trust to Threat of Police Line
The plight of Pesantren Al-Fath Jalen spans over a decade, reflecting a complex intersection of administrative misunderstandings and aggressive local revenue collection efforts. According to Naili, a representative and administrator of the pesantren, the institution’s journey with administrative documentation began around 2010. At the time, administrators approached the local Office of Religious Affairs (KUA) to secure a formal waqf (endowment) certificate for the property.
Naili recalled that the formalization process was notoriously lengthy and financially burdensome for the small community. During these proceedings, representatives from the KUA informed the school’s administrators that educational institutions operating as Islamic boarding schools were legally exempt from paying property taxes such as PBB. Because the leadership and staff were laypersons unfamiliar with complex tax statutes, they trusted the guidance provided by the religious affairs officials and proceeded without seeking further formal tax exemptions.
For over a decade, this understanding held true, and the pesantren operated peacefully, focusing entirely on community education and religious instruction. However, the situation deteriorated drastically in 2024 when the institution began receiving unexpected official property tax demand letters from the local regional revenue agency (Bapenda).
The administrative pressure culminated in early 2025, when administrators received a notice stating that the pesantren property faced the severe threat of being cordoned off with police lines due to accumulated unpaid taxes. For the aging leadership and the administration, the threat was devastating. Naili recounted that the stress of the impending enforcement action deeply impacted the late founder, Kiai Yasin, who passed away shortly after the shocking notice was issued.
Legislative Framework and Legal Exemptions
During her on-site visit to the Bekasi boarding school, Rieke Diah Pitaloka strongly criticized the actions of the regional revenue officers, characterizing the tax collection as a violation of existing legal frameworks. She emphasized that non-profit educational and religious foundations are explicitly protected under Indonesian tax regulations.
Pitaloka explicitly cited Article 38 of the prevailing regulations governing the Land and Building Tax (PBB). The statute clearly dictates that PBB objects do not apply to land and buildings owned or utilized exclusively for public interests in the fields of religion, social welfare, health, national education, and culture, provided that such use is strictly non-commercial and generates no profit.
“The foundation managed by my late brother does not seek profit. How dare they demand taxes? We will resolve this according to customary law standards,” Pitaloka stated firmly during her inspection. She further underscored the vital societal role played by traditional boarding schools, asserting that Islamic boarding schools effectively substitute for the state by providing education and moral guidance to underprivileged segments of society. “The pesantren has effectively taken over the responsibility of the state. Things like this certainly should not happen,” she added.
Local legislative representation was also present to address the grievance. Nyumarno, a member of the Bekasi Regency Regional House of Representatives (D DPRD), acknowledged the administrative failure and confirmed that local ordinances explicitly exempt non-commercial religious and educational institutions from property taxation.
“In Bekasi Regency, there are indeed established regulations stipulating that places of worship or non-commercial Islamic boarding schools can apply for a complete exemption from PBB payments,” Nyumarno explained during the site visit. However, he conceded that systemic flaws exist in the implementation phase. “In practice, tax bills sometimes arrive without prior socialization or administrative verification. For Pesantren Al-Fath, I will personally oversee the case to ensure that the property tax is permanently waived.”
Broader Implications for Islamic Boarding Schools in Indonesia
The incident at Pesantren Al-Fath Jalen is not an isolated case but rather symptomatic of a broader systemic friction between aggressive local revenue mobilization targets and the traditional social institutions of Indonesia. Islamic boarding schools, or pesantren, hold a foundational position in the nation’s educational landscape, predating modern state structures and serving millions of students, particularly in rural and semi-urban communities.
Under decentralized governance structures, local governments across Indonesia hold the authority to collect local taxes, including PBB, to finance regional development budgets. However, pressure on regional revenue agencies (Bapenda) to meet aggressive local tax collection targets has occasionally led to indiscriminate data-matching exercises. Automated tax generation systems frequently flag registered land parcels without properly cross-referencing institutional profiles, leading to erroneous billing of tax-exempt entities such as waqf lands, mosques, and traditional schools.
Experts and civil society organizations have frequently pointed out that administrative hurdles in processing formal tax exemptions often leave grassroots religious institutions vulnerable. While national laws grant sweeping exemptions for public-interest properties, the bureaucratic burden of applying for and maintaining these exemptions falls heavily on institutions with limited administrative capacity.
The public reaction to Pitaloka’s intervention highlights the deep emotional and cultural reverence accorded to pesantrens within Indonesian society. For millions, these institutions represent centers of spiritual integrity and community resilience. Consequently, bureaucratic attempts to exact property taxes from such entities are viewed not merely as administrative errors, but as institutional insensitivity.
Institutional Response and Path Forward
As the case of Pesantren Al-Fath Jalen gains national traction, attention has turned toward the Ministry of Finance and regional authorities to implement corrective safeguards. The direct appeal made by a senior legislator to Finance Minister Purbaya Yudhi Sadewa places pressure on central authorities to issue clearer guidelines and inter-agency coordination protocols between the Directorate General of Taxes, regional revenue offices, and the Ministry of Religious Affairs.
Local political actors in Bekasi have committed to resolving the immediate crisis facing the Al-Fath foundation through administrative remediation and formal exemption filings. Nevertheless, the incident serves as a stark reminder of the urgent need for systemic administrative reform to protect educational and religious institutions from unwarranted financial burdens, ensuring that the historical sanctuary provided by pesantrens remains preserved for future generations.