
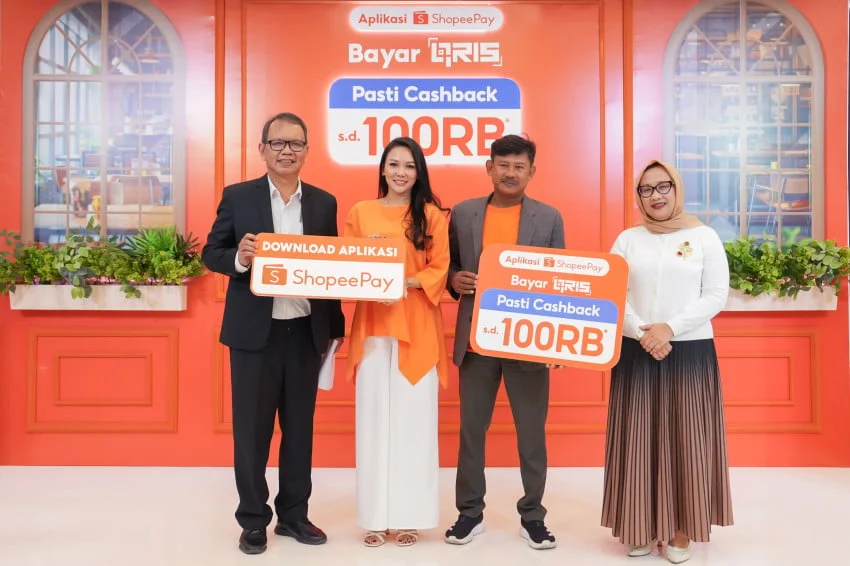
The integration of Quick Response Code Indonesian Standard (QRIS) into the daily transactional landscape of Indonesia has reached a pivotal juncture, as digital payment platforms like ShopeePay solidify their role in fostering a more inclusive and efficient financial ecosystem. This shift, driven by the strategic vision of Bank Indonesia (BI), reflects a broader national transition toward a cashless society, wherein QRIS serves as the primary bridge connecting millions of consumers with micro, small, and medium enterprises (MSMEs). During a high-profile event titled "Cara Baru Manfaatkan QRIS: Pengguna & Pengusaha UMKM Pasti Untung" held on September 16 in Jakarta, industry leaders and regulators emphasized that the ubiquity of QRIS is no longer merely a trend but a fundamental pillar of modern Indonesian commerce.
The Evolution of QRIS in the Indonesian Financial Landscape
The journey of QRIS began as a transformative initiative by Bank Indonesia to unify the fragmented digital payment landscape. Before its standardization, merchants were often overwhelmed by the need to display multiple QR codes for different e-wallet providers, leading to operational friction and customer confusion. The introduction of a single, interoperable QR code changed this trajectory. Since its official launch, QRIS has expanded rapidly, moving from large retail chains to the smallest street-side vendors.
According to historical data from Bank Indonesia, the growth of QRIS adoption has been exponential. By the end of 2023, the number of users had surpassed 45 million, with the vast majority of these being MSMEs. This digital transformation has been supported by payment service providers like ShopeePay, which have integrated QRIS into their core applications, allowing users to make seamless payments across millions of merchant locations. This interoperability ensures that regardless of which e-wallet a consumer prefers, the transaction is processed instantly, safely, and transparently.
Insights from Bank Indonesia: A Focus on Financial Inclusion
At the September 16 event, Fitria Irmi Triswati, Executive Director of the Payment System Policy Department at Bank Indonesia, underscored the significance of this widespread adoption. She highlighted that the development of QRIS is a cornerstone of Bank Indonesia’s broader mission to create a digital payment ecosystem that is not only secure and integrated but also highly efficient.
"The development of QRIS is a strategic component of our effort to build a financial ecosystem that is inclusive and robust," Triswati stated. "Current data indicates that 96.69% of the 45.46 million QRIS merchants are classified as MSMEs. This is a staggering figure that proves the democratization of digital finance is working. When small businesses can process payments as efficiently as large corporations, they gain better access to credit, improved record-keeping, and greater participation in the formal economy."
This assertion by Bank Indonesia highlights a critical socio-economic implication: the digitization of payments is a gateway to financial inclusion. By reducing the reliance on cash, businesses are better able to track their revenue, build a digital footprint, and eventually qualify for formal financial services, such as business loans and insurance products, which were previously inaccessible to them.
ShopeePay’s Role in Bridging the Gap
ShopeePay has emerged as a key facilitator in this ecosystem. By embedding QRIS support directly into the Shopee application, the platform has removed technical barriers for both the buyer and the seller. For the average Indonesian consumer, the convenience of having an e-wallet, a marketplace, and a payment gateway in a single interface is significant.
The platform’s strategy revolves around three core pillars: convenience, security, and integration. By ensuring that their infrastructure is compatible with the Bank Indonesia-mandated QRIS standard, ShopeePay ensures that its users can transact at any merchant displaying the QRIS logo. This ecosystem approach is vital because it creates a "network effect"—the more users adopt the system, the more valuable it becomes for merchants to participate, and vice versa.
Furthermore, the recent event served as a platform for ShopeePay to demonstrate how they are helping MSMEs transition from traditional cash-based bookkeeping to digital systems. By providing merchants with tools to monitor transactions in real-time, ShopeePay helps business owners optimize their inventory and cash flow management, which is often the biggest hurdle for small-scale entrepreneurs.

Supporting Data: The Scale of Digital Adoption
To understand the scale of this transformation, one must look at the macro data. The transition to QRIS is supported by the National Payment Gateway (GPN), which ensures that transactions are processed domestically, keeping costs low and data security high.
Data trends from the past three years show that transaction volume via QRIS has consistently seen double-digit growth. This is attributed to several factors:
- Low Barrier to Entry: Merchants do not require expensive point-of-sale (POS) terminals; a simple printed QR code suffices.
- Reduced Counterfeit Risk: Digital payments eliminate the risk of receiving counterfeit cash, a common issue for small merchants.
- Regulatory Backing: Bank Indonesia’s continuous updates to the QRIS framework—including the recent rollout of QRIS Tuntas (transfer, cash withdrawal, and cash deposit)—have expanded the utility of the service beyond simple retail payments.
As of late 2024, the total value of QRIS transactions has reached hundreds of trillions of Rupiah annually, representing a massive shift in how the Indonesian economy functions.
Implications for the Future: Beyond Payments
The widespread adoption of QRIS by platforms like ShopeePay has implications that extend far beyond simple transaction processing. Firstly, it facilitates the "formalization" of the informal economy. Many Indonesian MSMEs operate in the shadow economy, making it difficult for the government to track economic growth or provide targeted support. With QRIS, every transaction leaves a digital trail, providing the government with better data to formulate economic policies.
Secondly, it enhances consumer protection. Digital transactions are inherently more transparent and traceable than cash. Should a dispute arise, there is a clear electronic record of the transaction, which helps in conflict resolution between consumers and merchants.
Thirdly, the integration of QRIS is a foundational step toward the potential implementation of a Central Bank Digital Currency (CBDC) or "Digital Rupiah." By habituating the population to digital-first financial transactions, Bank Indonesia is essentially preparing the infrastructure for future financial innovations.
Challenges and the Road Ahead
Despite the rapid progress, challenges remain. Issues such as network stability in remote areas, digital literacy among older business owners, and cybersecurity threats require constant attention. Stakeholders at the September 16 event acknowledged that while adoption is high, the "quality" of usage—meaning the frequency and the complexity of services used—must continue to improve.
ShopeePay, in conjunction with other industry players, is currently focusing on educational initiatives. These initiatives aim to teach merchants how to leverage their transaction data for better business planning and how to protect themselves from digital fraud. This shift from "payment provider" to "business partner" is expected to be the next phase of the digital payment revolution in Indonesia.
Conclusion: A Collaborative Effort for National Prosperity
The collaboration between regulators, such as Bank Indonesia, and private entities like ShopeePay is essential for the continued success of the digital economy. The event in Jakarta served as a microcosm of this synergy, highlighting that the ultimate goal of these technological advancements is not just the digitization of money, but the improvement of lives for both the consumer and the entrepreneur.
As Indonesia moves toward its "Indonesia Emas 2045" (Golden Indonesia 2045) vision, the role of a robust, inclusive, and efficient digital payment system cannot be overstated. By empowering MSMEs and providing consumers with a seamless transactional experience, platforms like ShopeePay are ensuring that the digital revolution reaches every corner of the archipelago, effectively turning the QRIS code into a symbol of progress and economic resilience. The future of Indonesian finance is increasingly digital, and the infrastructure currently being built is the bedrock upon which the nation’s future prosperity will rest.
