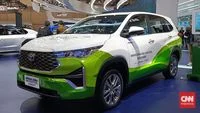
The future of Indonesia’s automotive landscape stands at a critical juncture as the transition toward electrification accelerates across Southeast Asia’s largest economy. Amid a surge in consumer interest and government initiatives promoting green mobility, domestic manufacturing associations have stepped forward to emphasize the absolute necessity of rigorous regulatory frameworks. The Association of Automotive Component Industries, known locally as Gabungan Industri Alat-alat Mobil dan Motor (GIAMM), has formally stated that mandatory implementation of the Domestic Component Level, or Tingkat Komponen Dalam Negeri (TKDN), policies for electric vehicles (EVs) must take precedence over the simple importation of completely built-up (CBU) units.
According to GIAMM Secretary-General Rachmat Basuki, enforcing strict local content thresholds is not merely a bureaucratic hurdle, but a proven catalyst for driving product localization and reinforcing the foundation of national industrialization. Speaking in Jakarta, Rachmat highlighted that relying solely on imported finished vehicles bypasses the critical process of technological transfer and domestic supply chain integration. The government, therefore, faces an urgent mandate to incentivize and compel global and local manufacturers to maximize domestic component utilization, thereby laying the groundwork for a robust, self-sustaining domestic EV ecosystem.
The economic logic underpinning this stance is rooted in economies of scale. As domestic manufacturing volumes expand, production costs decline per unit, which in turn enhances the global and regional competitiveness of Indonesian-made automotive products. By insisting on domestic value addition from the outset of the EV transition, Indonesia aims to avoid the trap of becoming a mere consumer market and instead solidify its position as a vital manufacturing hub within the global supply chain.
Historical Precedent and the Evolution of Indonesian Automaking
To understand the strategic importance of the current TKDN policies for electric vehicles, industry analysts often look back at the formative decades of Indonesia’s automotive sector. The success of localized manufacturing is not a theoretical concept; it has a tangible precedent in the evolution of the country’s automotive industry during the 1970s.
During that era, the domestic market was heavily reliant on imported vehicles that offered little to no spillover benefits for local engineering or component manufacturing capabilities. Recognizing the limitations of this import-dependent model, the government instituted early localization frameworks. Gradually, the market transitioned from importing finished goods to establishing domestic assembly plants. Over subsequent decades, this foundational shift catalyzed the growth of a secondary tier of local enterprises capable of manufacturing intricate vehicle parts, ranging from chassis frames to electrical wiring harnesses.
This historical trajectory transformed conventional internal combustion engine (ICE) vehicles into a mature sector. Today, traditional vehicles manufactured within Indonesia boast impressive localization metrics, with local content integration frequently exceeding 80 percent. This high degree of localization has successfully fostered a comprehensive ecosystem encompassing raw material suppliers, component fabricators, tier-one and tier-two suppliers, as well as specialized workforce training facilities.
GIAMM argues that the ongoing electrification wave must replicate this historical success rather than short-circuit it through liberalized importation policies. Ensuring that the shift toward electric mobility is tightly coupled with local component integration is essential to safeguarding the livelihoods of hundreds of thousands of workers employed across the domestic automotive supply chain.
Current Market Dynamics and Regulatory Roadmaps
The urgency of enforcing TKDN policies becomes starkly apparent when examining current market statistics. Official data illustrates a rapidly expanding market for electrified transport, though imported units and assembly models with low initial local content still occupy a substantial share of the commercial landscape.
Up to August 2026, total national car sales reached 599,491 units. Within this aggregate figure, battery electric vehicles (BEVs) accounted for 101,171 units, representing approximately 16.88 percent of the total automotive market. This signifies a notable milestone, demonstrating that consumer adoption of electric vehicles has surpassed initial conservative projections and is scaling at a pace that demands immediate, decisive industrial policy alignment.
To manage this transition and ensure that domestic industries capture the economic value of this growing segment, the Indonesian government has implemented a phased regulatory roadmap for EV local content requirements:
- Year 2026: Manufacturers are required to achieve a minimum TKDN compliance level of 40 percent.
- Year 2027: The mandatory local content threshold increases significantly to 60 percent.
- Year 2030: A strict requirement of 80 percent local content comes into full effect for all applicable EV models produced and sold domestically.
Rachmat expressed optimism that as these thresholds escalate over the coming years, regulatory enforcement will increasingly target high-value, core components of electric vehicles rather than just auxiliary parts. Specifically, the localization focus must pivot toward the heart of the electric vehicle architecture: the battery system and its foundational raw materials.
"Moving forward, we want to be deeply involved in the core manufacturing processes," Rachmat noted, emphasizing that domestic industries possess the capability to absorb advanced technologies provided that policy frameworks continuously protect and incentivize local participation.
Ministry Perspectives on Upstream Integration
The Ministry of Industry has consistently echoed the necessity of enforcing the 2030 threshold while identifying the precise technological bottlenecks that must be overcome to achieve true industrial independence. Setia Diarta, Director General of Metal, Machinery, Transport Equipment, and Electronics (ILMATE) at the Ministry of Industry, previously underscored that meeting the ambitious 80 percent TKDN target by the end of the decade depends heavily on upstream investments.
According to the Ministry, assembling battery packs from imported cells will no longer suffice as the regulatory framework matures. The ultimate driver of high TKDN value within the electric vehicle sector must originate from the domestic production of battery cells and the local processing of critical minerals, most notably nickel, of which Indonesia holds some of the world’s largest reserves.
"The most crucial element that will trigger a genuine leap in TKDN value here is the battery cell itself, alongside the production of battery modules," Setia Diarta explained during a recent industry briefing.
This perspective aligns with Indonesia’s broader economic strategy of downstreaming (hilirisasi). For years, the government has restricted the raw export of unprocessed nickel ore, compelling mining companies to construct domestic smelting facilities. By bridging the gap between raw mineral extraction, refined chemical processing, battery cell manufacturing, and final vehicle assembly, Indonesia aims to capture the entirety of the electric vehicle value chain within its national borders.
Implications for Foreign Investors and Global Automakers
The rigid enforcement of ascending TKDN targets carries profound implications for international automotive brands seeking to capture a share of Indonesia’s lucrative consumer market. Global manufacturers, particularly from Asia, Europe, and the United States, have historically relied on exporting vehicles directly to emerging markets or utilizing low-cost component assembly models that require minimal capital expenditure in the destination country.
Under Indonesia’s current regulatory framework, these strategies are no longer viable for long-term market dominance. Global original equipment manufacturers (OEMs) must now commit to substantial capital investments, establish localized research and development partnerships, and collaborate with local component makers represented by organizations like GIAMM.
While some multinational corporations initially expressed concern regarding the strict compliance timelines—citing the high capital costs associated with setting up battery cell manufacturing facilities and advanced component testing laboratories—government officials and industry advocates maintain that the sheer size of the Indonesian market serves as sufficient leverage. With a population exceeding 275 million and a burgeoning middle class, access to Indonesia’s domestic consumer base is contingent upon contributing to the nation’s industrial development goals.
Furthermore, compliance with TKDN standards opens up strategic advantages for automakers. Vehicles that meet the mandated local content thresholds qualify for various government fiscal incentives, luxury tax exemptions, and subsidies, making them significantly more attractive to price-sensitive domestic consumers. Additionally, producing vehicles within Indonesia positions manufacturers to utilize the country as an export base for neighboring ASEAN nations and broader international markets, leveraging existing regional trade agreements.
Challenges on the Horizon for Local Component Makers
Despite the optimistic outlook presented by industry associations and government bodies, the path to achieving an 80 percent TKDN level by 2030 is fraught with structural and technical challenges. Local component manufacturers face rigorous demands regarding quality control, precision engineering, and technological adaptability.
Transitioning from the production of internal combustion engine components—such as exhaust systems, pistons, and traditional transmission gears—to manufacturing EV-specific components requires a radical overhaul of factory floors, retraining of workforces, and substantial financial investment in advanced machinery. Components such as electric motors, power control units, thermal management systems, and high-voltage battery management systems demand levels of precision and electronic sophistication that exceed traditional automotive manufacturing standards.
Moreover, small and medium-sized enterprises (SMEs) operating within the lower tiers of the automotive supply chain often struggle to secure the capital required to upgrade their technological capabilities. Without targeted financial assistance, low-interest modernization loans, and government-backed technical training programs, a risk remains that smaller local suppliers may be marginalized, leaving the high-value manufacturing segments exclusively in the hands of major foreign conglomerates.
GIAMM has repeatedly called upon policymakers to ensure that the implementation of TKDN regulations is accompanied by comprehensive support mechanisms for local suppliers. This includes fostering joint ventures between established global technology leaders and domestic component producers to facilitate seamless knowledge transfer and capacity building.
Broader Economic Impact and Strategic Outlook
The debate over electric vehicle localization and TKDN policies transcends the automotive sector, touching upon core elements of Indonesia’s national economic sovereignty and long-term development strategy. As global climate commitments drive an irreversible pivot toward green energy and sustainable transportation, countries that successfully master the entire EV supply chain will secure significant economic advantages in the decades to come.
By insisting on domestic value addition, Indonesia is positioning itself not merely as a passive consumer of global technological trends, but as an active architect of its industrial destiny. The integration of local component industries into the high-tech EV supply chain protects domestic employment, fosters local innovation, and ensures that the wealth generated by the green transition remains within the national economy.
As the industry navigates the roadmap toward the 2026 milestone of 40 percent local content and looks ahead to the ultimate 80 percent target in 2030, the collaboration between government regulators, industry associations like GIAMM, and international manufacturers will be paramount. Balancing the need for rapid electrification with the imperative of deep industrialization remains the definitive challenge and opportunity for Indonesia’s automotive sector in the modern era.