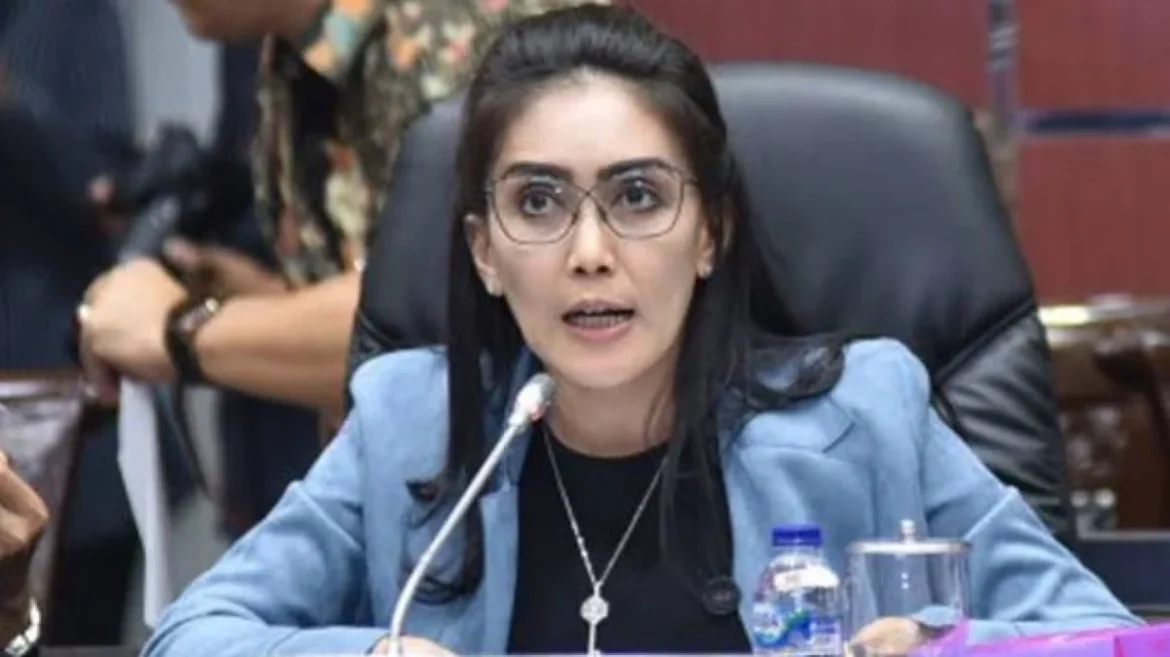
The intersection of state taxation policy and religious educational institutions in Indonesia has once again drawn intense public scrutiny following a recent incident in Bekasi, West Java. Rieke Diah Pitaloka, a member of Commission VI of the House of Representatives (DPR RI) representing the Indonesian Democratic Party of Struggle (PDI-P), expressed deep indignation upon discovering that a local Islamic boarding school, or pesantren, was being pursued for substantial arrears on its Land and Building Tax (Pajak Bumi dan Bangunan, or PBB). The institution in question, Pesantren Al-Fath Jalen, located in Tambun Utara, Bekasi Regency, was established by the late Kiai Yasin and has long served the local community as a non-commercial hub for religious and educational development.
The controversy erupted into the public sphere after Rieke published a video on her verified Instagram account under the handle @riekediahp, utilizing the digital campaign channel Viral for Justice with the hashtag #SavePesantrenIndonesia. In the video, which quickly circulated across various social media platforms, the prominent legislator could be seen demanding the immediate attention of the Minister of Finance, Purbaya Yudhi Sadewa. Rieke argued that the imposition of property taxes on a non-profit religious and educational sanctuary directly violates existing statutory regulations and undermines the foundational social contributions that such institutions provide to the republic.
Chronology of the Dispute at Pesantren Al-Fath
The administrative conflict surrounding Pesantren Al-Fath Jalen dates back well over a decade, rooted in a combination of administrative miscommunication, public misunderstanding, and shifting local governance practices. According to Naili, a key administrator at the boarding school who recounted the history of the property to Rieke during her visit, the school’s leadership had maintained a long-standing belief that the institution was entirely exempt from property taxes.
This belief originated around 2010, when representatives of the pesantren visited the local Office of Religious Affairs (KUA) to process the formal land waqf (endowment) certificates for the property. At the time, administrators were informed by local KUA officials that educational and religious institutions operating as waqf lands were legally exempted from PBB obligations. Given the complexity and high cost associated with bureaucratic land administration at the time, and relying on the guidance provided by state religious officials, the school’s founders trusted the verbal assurance and treated the property as tax-exempt.
For nearly a decade and a half, the pesantren operated under this assumption, dedicating its limited financial resources entirely to student instruction, community outreach, and the maintenance of religious facilities. However, the operational landscape shifted dramatically in 2024. The foundation began receiving formal tax collection notices from the local regional revenue authorities. The situation escalated rapidly in early 2025, when administrators were reportedly threatened with a police line on the property due to accumulated unpaid taxes—an alarming prospect for a religious institution. Naili noted that the escalating administrative pressure deeply distressed the late Kiai Yasin, who passed away not long after the threats of asset seizure were communicated to the school.
Legal Framework and Statutory Tax Exemptions
The core of the controversy centers on the legal protection afforded to non-profit public-interest facilities under Indonesian tax law. During her site visit, Rieke Diah Pitaloka explicitly referenced statutory provisions governing the collection of the Land and Building Tax, pointing specifically to regulatory frameworks that safeguard public-interest spaces.
Under national guidelines, including regulations pertaining to regional taxes and retributions, objects utilized solely for public interest purposes in the fields of religion, social welfare, health, education, and national culture are legally exempt from PBB, provided that the underlying land and structures are not operated with the intent to generate commercial profit. Rieke emphasized that Pesantren Al-Fath, like thousands of similar institutions across the Indonesian archipelago, functions as an extension of social welfare and educational safety nets that the state would otherwise be financially obligated to provide.
"The pesantren has essentially taken over the responsibility of the state in educating the public. Things like this certainly should not happen," Rieke stated firmly during her inspection of the Bekasi facility. She added that the foundation does not operate as a commercial enterprise and characterized the aggressive pursuit of tax arrears by regional revenue officers as legally baseless and culturally insensitive.
Local Governance and Institutional Oversight
Addressing the systemic failures that allowed the tax billing to occur, local legislative representation stepped forward to offer assistance and clarify regional bylaws. Nyumarno, a member of the Bekasi Regency Regional House of Representatives (DPRD), was present during the legislative visit and corroborated the school administration’s assertions regarding statutory exemptions.
According to Nyumarno, regional regulations in Bekasi Regency clearly stipulate that places of worship and non-commercial Islamic boarding schools are fully eligible for PBB exemption status. However, he acknowledged that administrative bottlenecks and a lack of proactive coordination between regional revenue agencies and local communities often lead to systemic errors.
"In Bekasi Regency, there is indeed an existing regulation stating that places of worship or non-commercial Islamic boarding schools can apply for PBB exemption," Nyumarno explained. He admitted, however, that in practical implementation, tax bills are frequently dispatched automatically through computerized assessment systems without adequate field verification or prior social outreach. To rectify the situation at Pesantren Al-Fath, Nyumarno committed to providing direct legal and administrative accompaniment to ensure the cancellation of the tax bills and the formal securing of the school’s tax-exempt status.
Broader Implications for Pesantren Across Indonesia
The public outcry led by Rieke Diah Pitaloka highlights a recurring systemic vulnerability faced by traditional religious and educational institutions throughout Indonesia. Pesantrens, many of which operate on modest donations, agricultural yields, and community goodwill, frequently lack the administrative infrastructure required to navigate complex bureaucratic compliance procedures.
When regional governments push to maximize local revenue generation (Pendapatan Asli Daerah, or PAD), decentralized tax agencies occasionally target institutional landholdings without properly cross-referencing waqf registries or public-interest exemptions. This disconnect frequently results in administrative friction, public backlash, and unnecessary distress for community leaders and religious scholars who dedicate their lives to public education.
Analysts note that the high-profile involvement of national lawmakers in the Pesantren Al-Fath case may prompt the Ministry of Finance and regional administrative bodies to review automated tax assessment protocols. Ensuring better data integration between the Ministry of Religious Affairs, regional revenue offices (Bapenda), and local land offices (BPN) could prevent similar administrative errors from recurring. For Pesantren Al-Fath, the immediate priority remains securing official administrative relief so that the legacy of the late Kiai Yasin can continue to serve the community free from the threat of asset seizure and financial penalties.